DOCUMENT
Order of 31 January 1975 on the application of Articles 10, 11 and 12 of the Convention between Spain and the Kingdom of the Netherlands on the avoidance of double taxation of income taxes.
31.01.1975 · BOE-A-1975-3136
Illustrated sir:
The Convention between Spain and the Kingdom of the Netherlands on the prevention of double taxation of income and property taxes was signed on 18 June 1971, the exchange of instruments of ratification took place on 20 September 1972, and the publication in the Official Gazette of the State of 16 October 1972 (No. 248 of 1972). The application of some of the provisions of the Convention, such as those relating to dividends, determines the desirability of establishing, in accordance with article 30 of the treaty text, rules governing the procedure to be followed for the better effectiveness of the limits set out in those provisions. The same applies to certain interests and royalties.
The guidelines set out in the regulations of previous international conventions of the same nature are generally followed, introducing the peculiarities imposed by the specialities of the tax system of the Kingdom of the Netherlands.
This Ministry has provided for:
First. Income covered by Articles 10 and 11 of the Convention.
(A) Residents of Spain.
Interest is not subject to withholding tax in the Kingdom of the Netherlands, so there is no need to regulate any procedure applying the conventional limitation.
With regard to dividends, persons or entities resident in Spain within the meaning of Article 4 of the Convention shall observe the following procedure for the application of the conventional limits:
(a) General assumption (article 10.2 of the Convention).
Persons or entities resident in Spain who receive dividends from Dutch sources may request a reduction in the source or a refund of the excess of the Dutch tax withheld at the source. This excess is made up of the difference between the tax withheld and the tax due under the limit laid down in Article 10 of the Convention.
The application must be made in the form ‘Inkomstenbelasting number 92-SP’. This bilingual form, the third copy of which is annexed to this Order, shall be provided by the Spanish Treasury Delegations.
Once the form has been completed by the recipient of the dividends, the International Conventions Section of the Treasury Delegation, or the Office responsible for the said Service where the said Section does not exist, shall extend the certificate of residence, taking into account the records of the aforementioned Offices, and, where appropriate, the national identity card, passport or document certifying the residence, the display of which may be required, withserving the second copy of the form.
The first copy shall be sent, prior to the payment of the dividends, to the Entity which gives effect to the income, in accordance with paragraph 3 (a) of the Instructions, the Spanish version of which is given in Annex 1 to this Order in the event of a request for reduction.
Where the request for a refund is requested, either because the request for a reduction could not have been made in time, or because the necessary circumstances did not meet, in accordance with the text of Form 92-SP, the request must be sent within two years of the end of the calendar year in which the tax was required in the Kingdom of the Netherlands.
The third copy shall be addressed to the persons referred to in paragraphs ‘3.o, b, i’ or ‘3.o, b, ii’ of the Instructions contained therein and reproduced in Annex 1, as appropriate.
(b) Special assumption of some intersocial dividends (article 10.3 (a) of the Convention).
In this case, the use of the form is not specified, only the Spanish company receiving the form being communicated to the Dutch debtor company and the corresponding request from the Dutch debtor to the tax administration of the Kingdom of the Netherlands to obtain the reduction in the source or the refund.
B) Residents of the Kingdom of the Netherlands.
(a) Dividends and interest from Spain received by persons or entities which, pursuant to article 4 of the Convention have the status of residents of the Kingdom of the Netherlands, shall be taxed in Spain by withholding tax, carried out within the limits set out in articles 10 and 11 of that text. In order for these limits to be applied, the request must be made to the Spanish tax authorities.
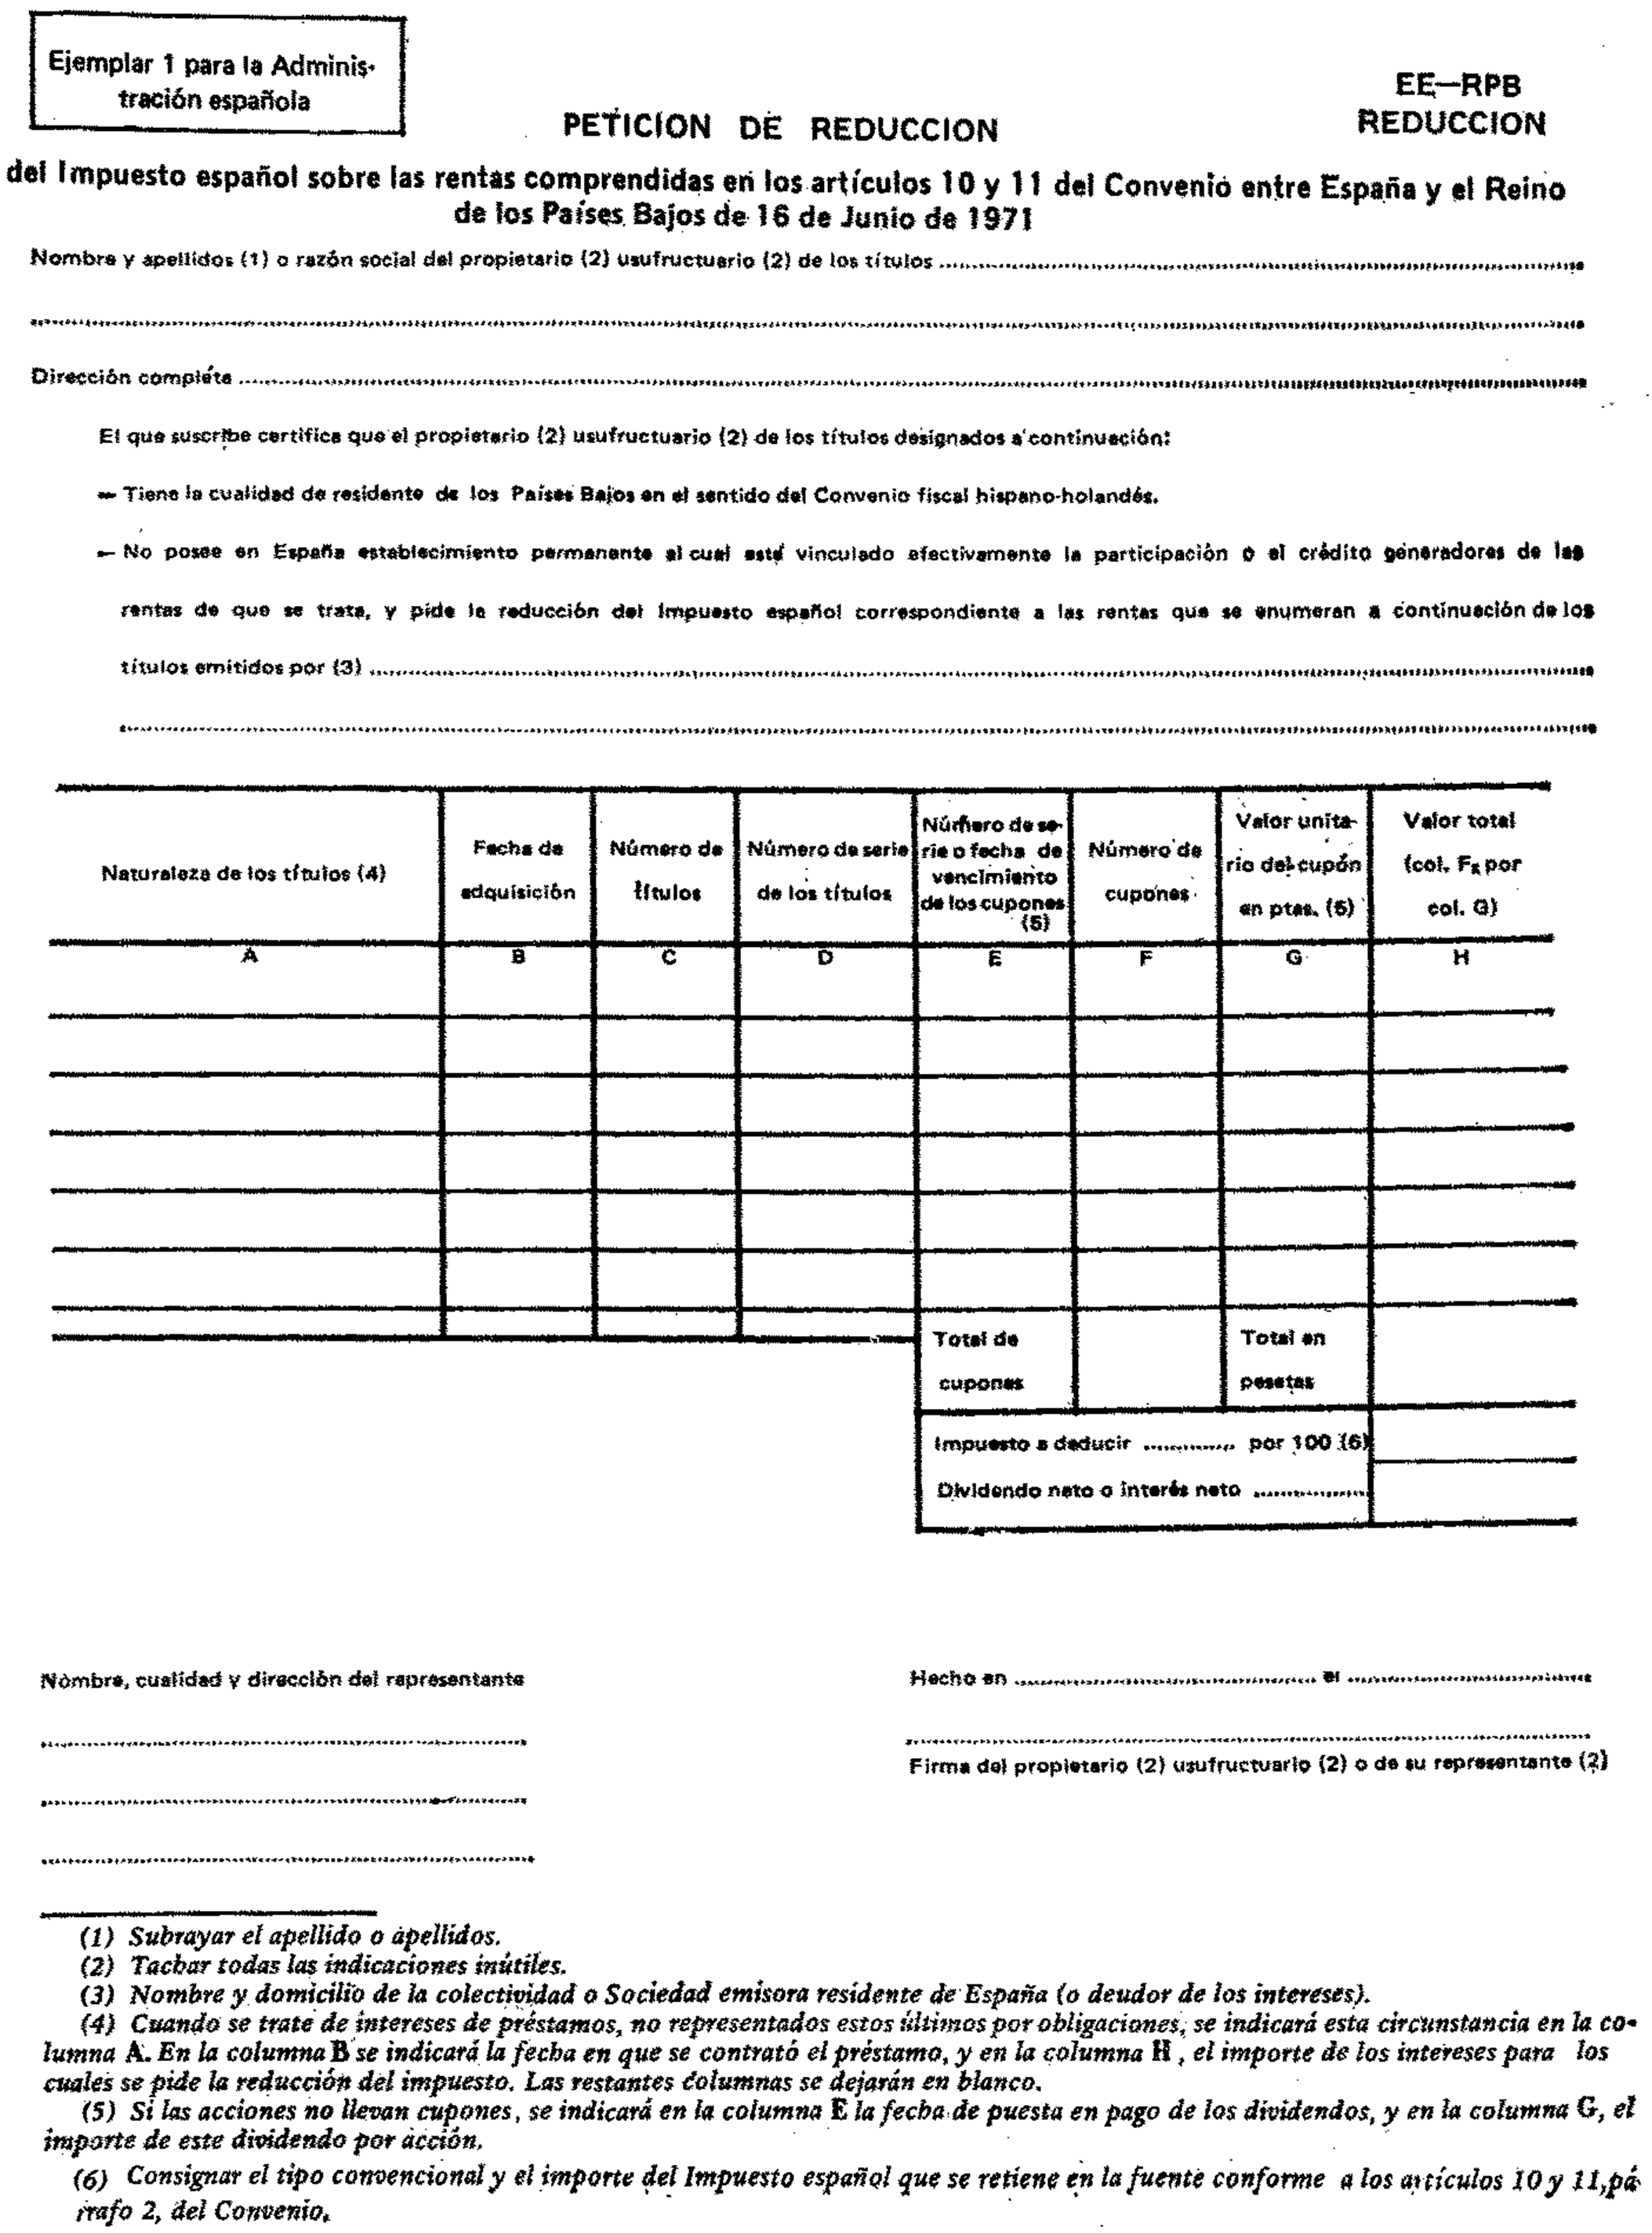
(b) The application shall necessarily be made in the model form EE-RPB-REDUCTION, which appears as annex number 2 to this Order. The form will be provided by the Ministry of Finance (Department of Tax Service Organization) in The Hague. Once the form has been completed and extended by the competent office of the Kingdom of the Netherlands, the beneficiary of the dividends or interest shall forward the two copies drawn up in Spanish to the resident person or entity of Spain, which is responsible for the income expressed. This person or entity, when paying dividends or interest, shall levy the Spanish Capital Income Tax, applying the limits of the Convention (Articles 10 and 11).
The same person will accompany the tax declaration-liquidation that must be submitted by regulation, one of the copies of the form, as proof that the tax withholding has been carried out, taking into account the conventional limit.
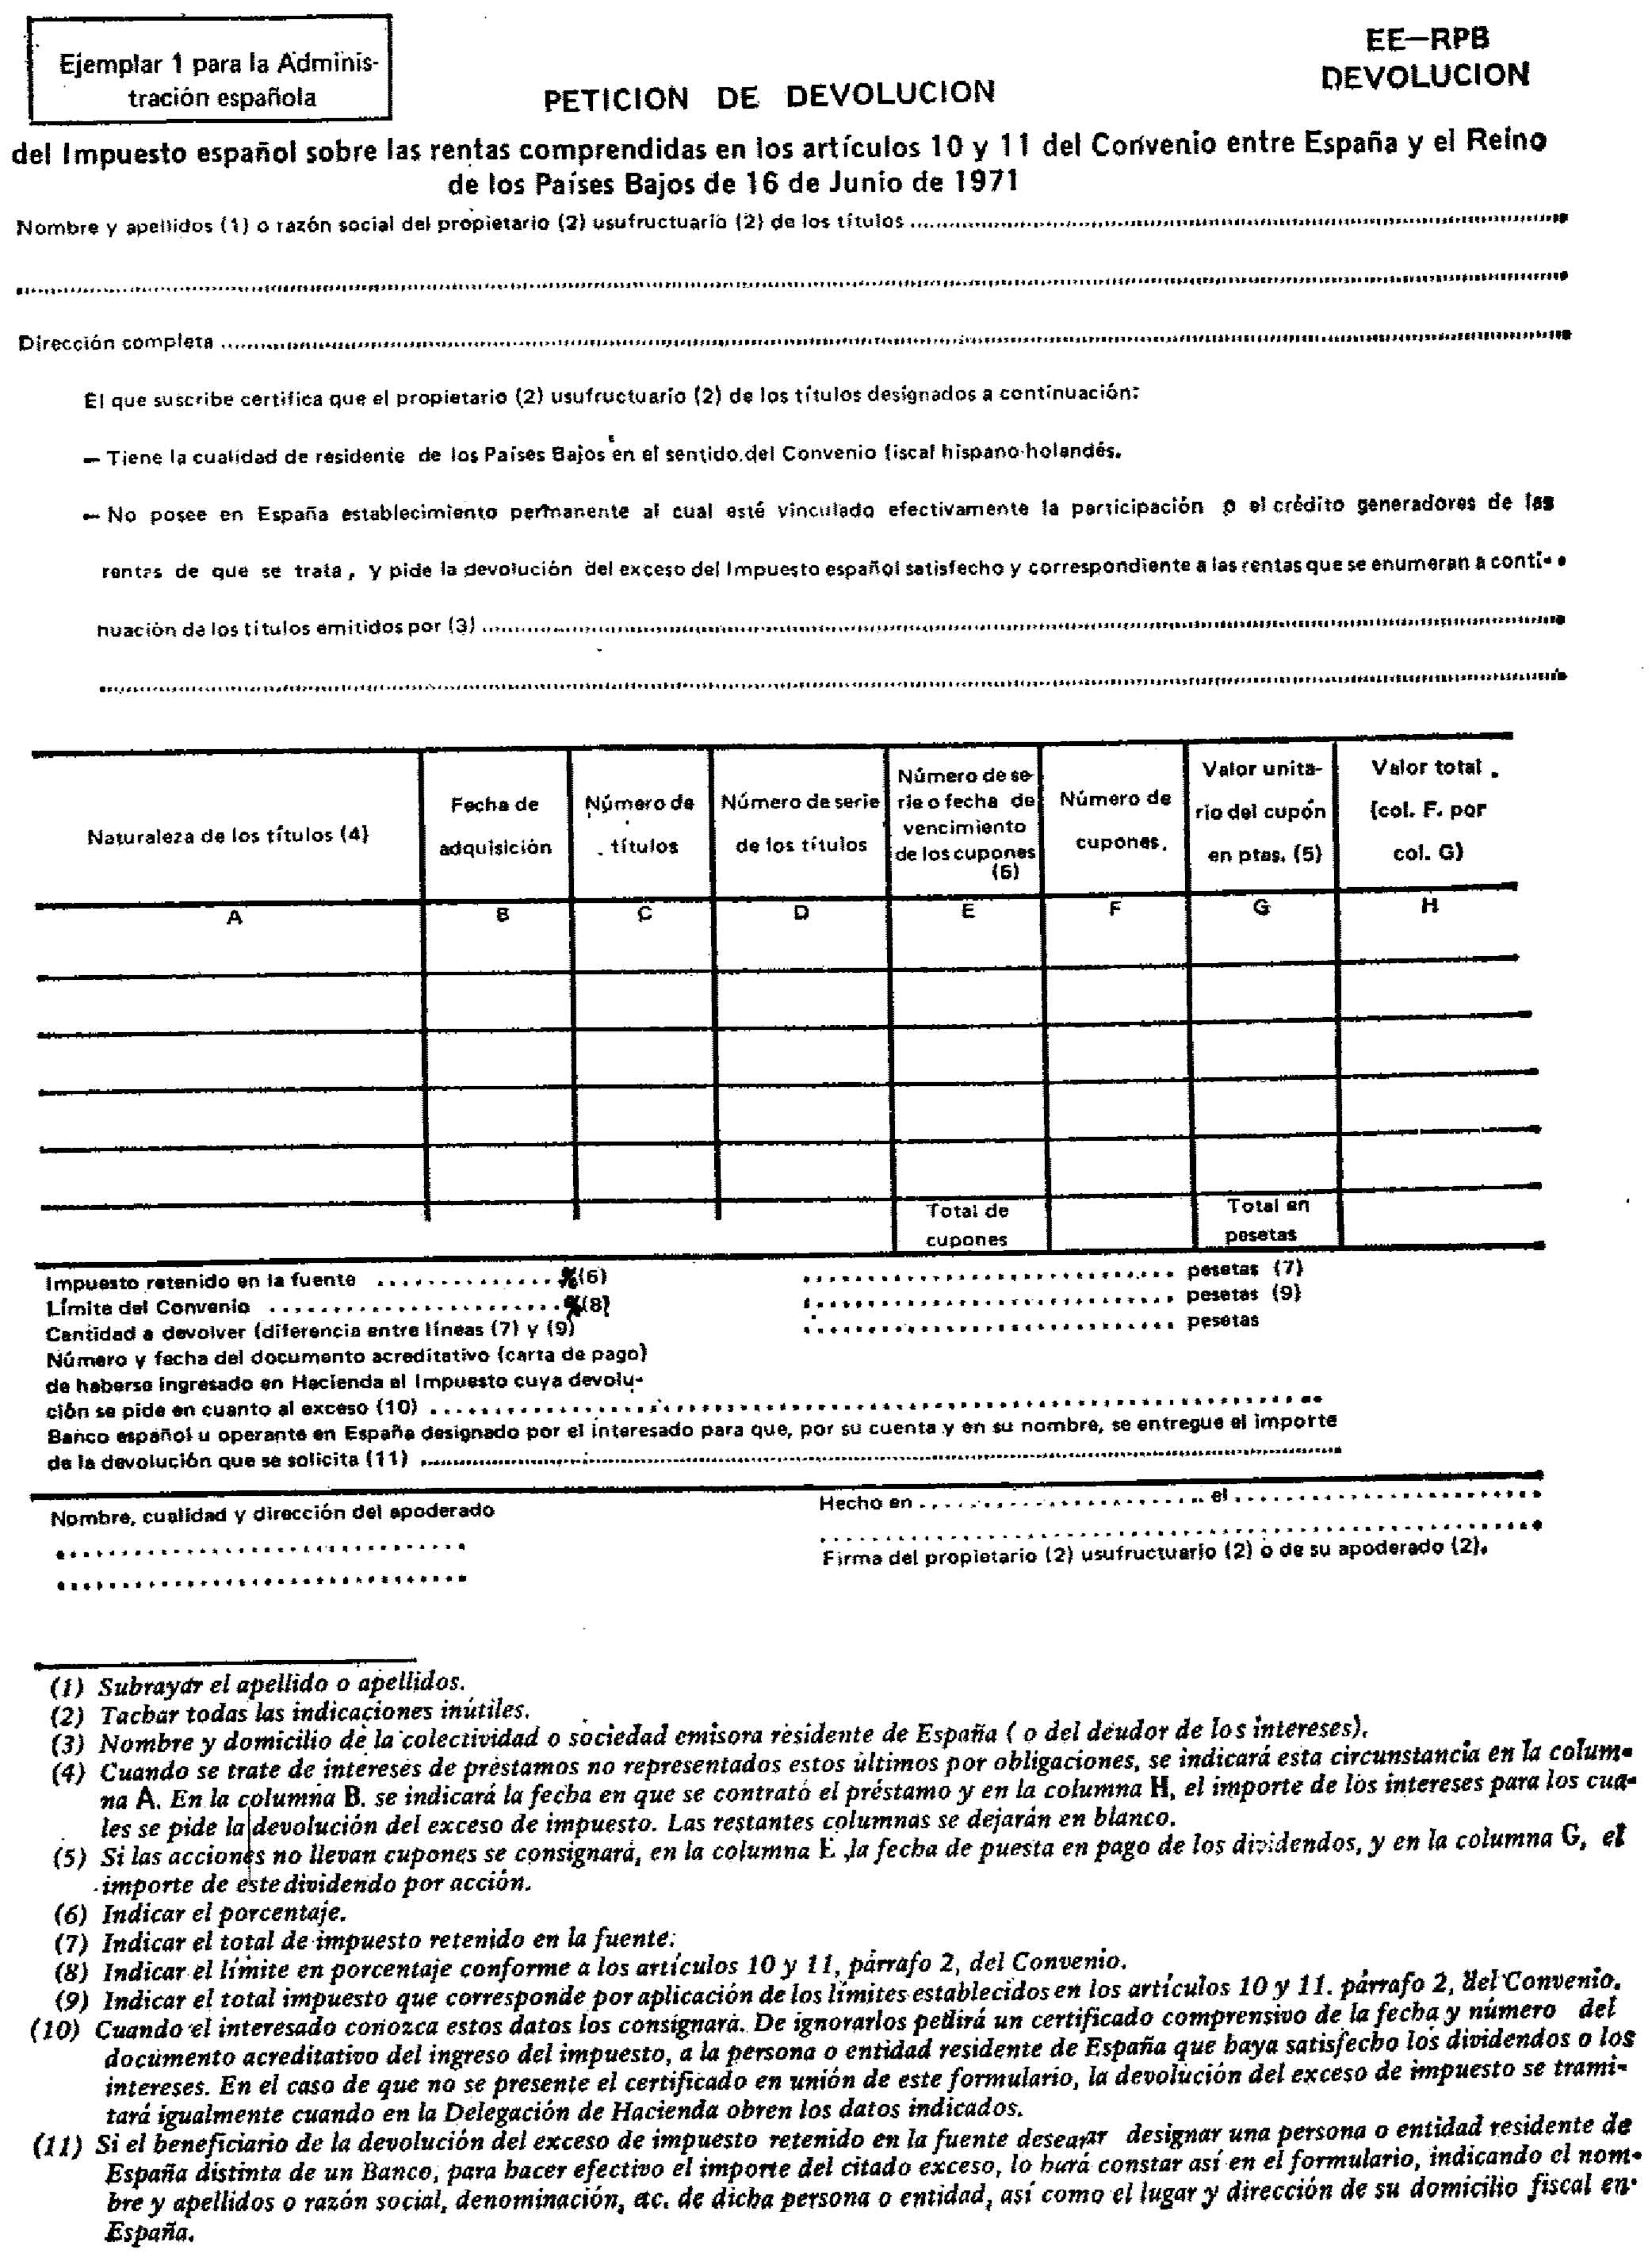
(c) If the procedure of reduction has not been used and the tax has been withheld, according to the rules of the common legislation, the application of the conventional limit for refund of the excess tax withheld can be achieved.
The application will be made in the model EE-RPB-DEVOLUTION (Annex 3 of this Order), which must be provided by the Hague Office indicated above. Upon completion and extension of the residence certificate, the copy in Spanish will be sent to the Treasury Delegation of the domicile of the debtor of the income.
This request must be accompanied by a certificate issued by the person or entity obliged to withhold the tax, stating the date and number of the letter of payment of the income in which the retention of the beneficiary was included.
Where the data are taken directly by the Administration, they shall be recorded in the file by means of diligence. If the certification is not accompanied by the application, and if the information to be included in the application is not recorded in the respective Treasury Delegation, the Management Office shall require the applicant to make the missing payment within 30 days.
Where the beneficiary of dividends or interest is acting by means of a person representing him, the relevant power of proof shall also be attached to the application.
The request for a refund shall be made at the relevant Treasury Delegation within two years of the end of the calendar year in which the tax was required. For this purpose, the date of entry shall be understood as the last day of the period within which the person or entity that withheld the tax is required to make it.
The file shall be processed by the International Conventions Section, or, failing that, by the Office responsible for the Service, in the manner set out in article 6 of Decree No. 363/1971 of 25 February, except for the time limit. The repayment agreement shall be issued by the Treasury Delegate.
(d) Several refunds may be requested on the same form when all refunds are within the time limit referred to in point (c) above, provided that they correspond to revenue made in the same Treasury Delegation.
Second. Income covered by Article 12 of the Convention.
(A) Residents of Spain.
In the absence of a Dutch levy on royalties, no procedure is required.
B) Residents of the Kingdom of the Netherlands.
Fees from Spain received by persons or entities who: under Article 4 of the Convention, have the status of residents of the Netherlands, shall be taxed in Spain on the income tax of capital, by withholding tax carried out within the limit set out in Article 12 of that text. This limited retention shall be applied by the resident debtor of Spain without the need for the resident creditor of the Netherlands to make any request to the Spanish tax authorities.
The tax declaration to be submitted by the debtor of the royalties shall necessarily state that the beneficiary of the royalties is resident in the Netherlands and shall also state the circumstances in the respective documents issued for the use or grant of the use of the rights and elements in general contained in Article 12 of the Convention. Where the debtor of the royalties retains the Spanish tax, according to the application of the rules and tax rates contained in the Spanish common law, as if there were no agreement, the resident person or entity of the Netherlands, beneficiary of such fees, may request the Spanish tax authorities to refund the excess Spanish tax retained at the source. No special form shall be required for the return request. The application shall be accompanied by a document proving the status of resident of the Netherlands within the meaning of the Convent issued by the tax authorities of the Netherlands and the certification referred to in paragraph 1(b) (c) of this Order, including the receipt of the tax on the fees in question.
Except in the specific subject matter of forms, the returns referred to in the preceding paragraph shall be governed by the provisions which, with reference and interest, are contained in the completed number indicated.
Third. Certificates.
Within their respective powers of territorial order, the Sections of International Conventions of the Treasury Delegations, or, failing that, the Offices liquidated the agreed taxes, shall, subject to appropriate checks, issue the certificates of residence which are requested in writing, for the purposes of applying the Agreement, by persons and entities having the status of residents of Spain within the meaning of Article 4 of the Agreement.
Without prejudice to the information and background provided by the Offices in question, in order to prove the fact of the residence, the applicant who exhibits the documents referred to in paragraph 1 (A) (a) (3) of this Order may be required to do so.
It shall also be the responsibility of the Offices concerned to issue other certificates which are requested from them by the persons and entities concerned, provided that they are intended to apply any of the provisions of the Convention by Spain or the Netherlands.
What I communicate to V. I. for its knowledge and effects.
God save V. I. Many years.
Madrid, 31 January 1975.
ALBA AND GRACIA HAIR
Ilmo. Sir. Secretary-General quiet.
ANNEX NUMBER 1
English rendering of a scanned annex (unverified OCR). The original facsimile is retained below for comparison.
Automatic English OCR transcription (unreviewed)
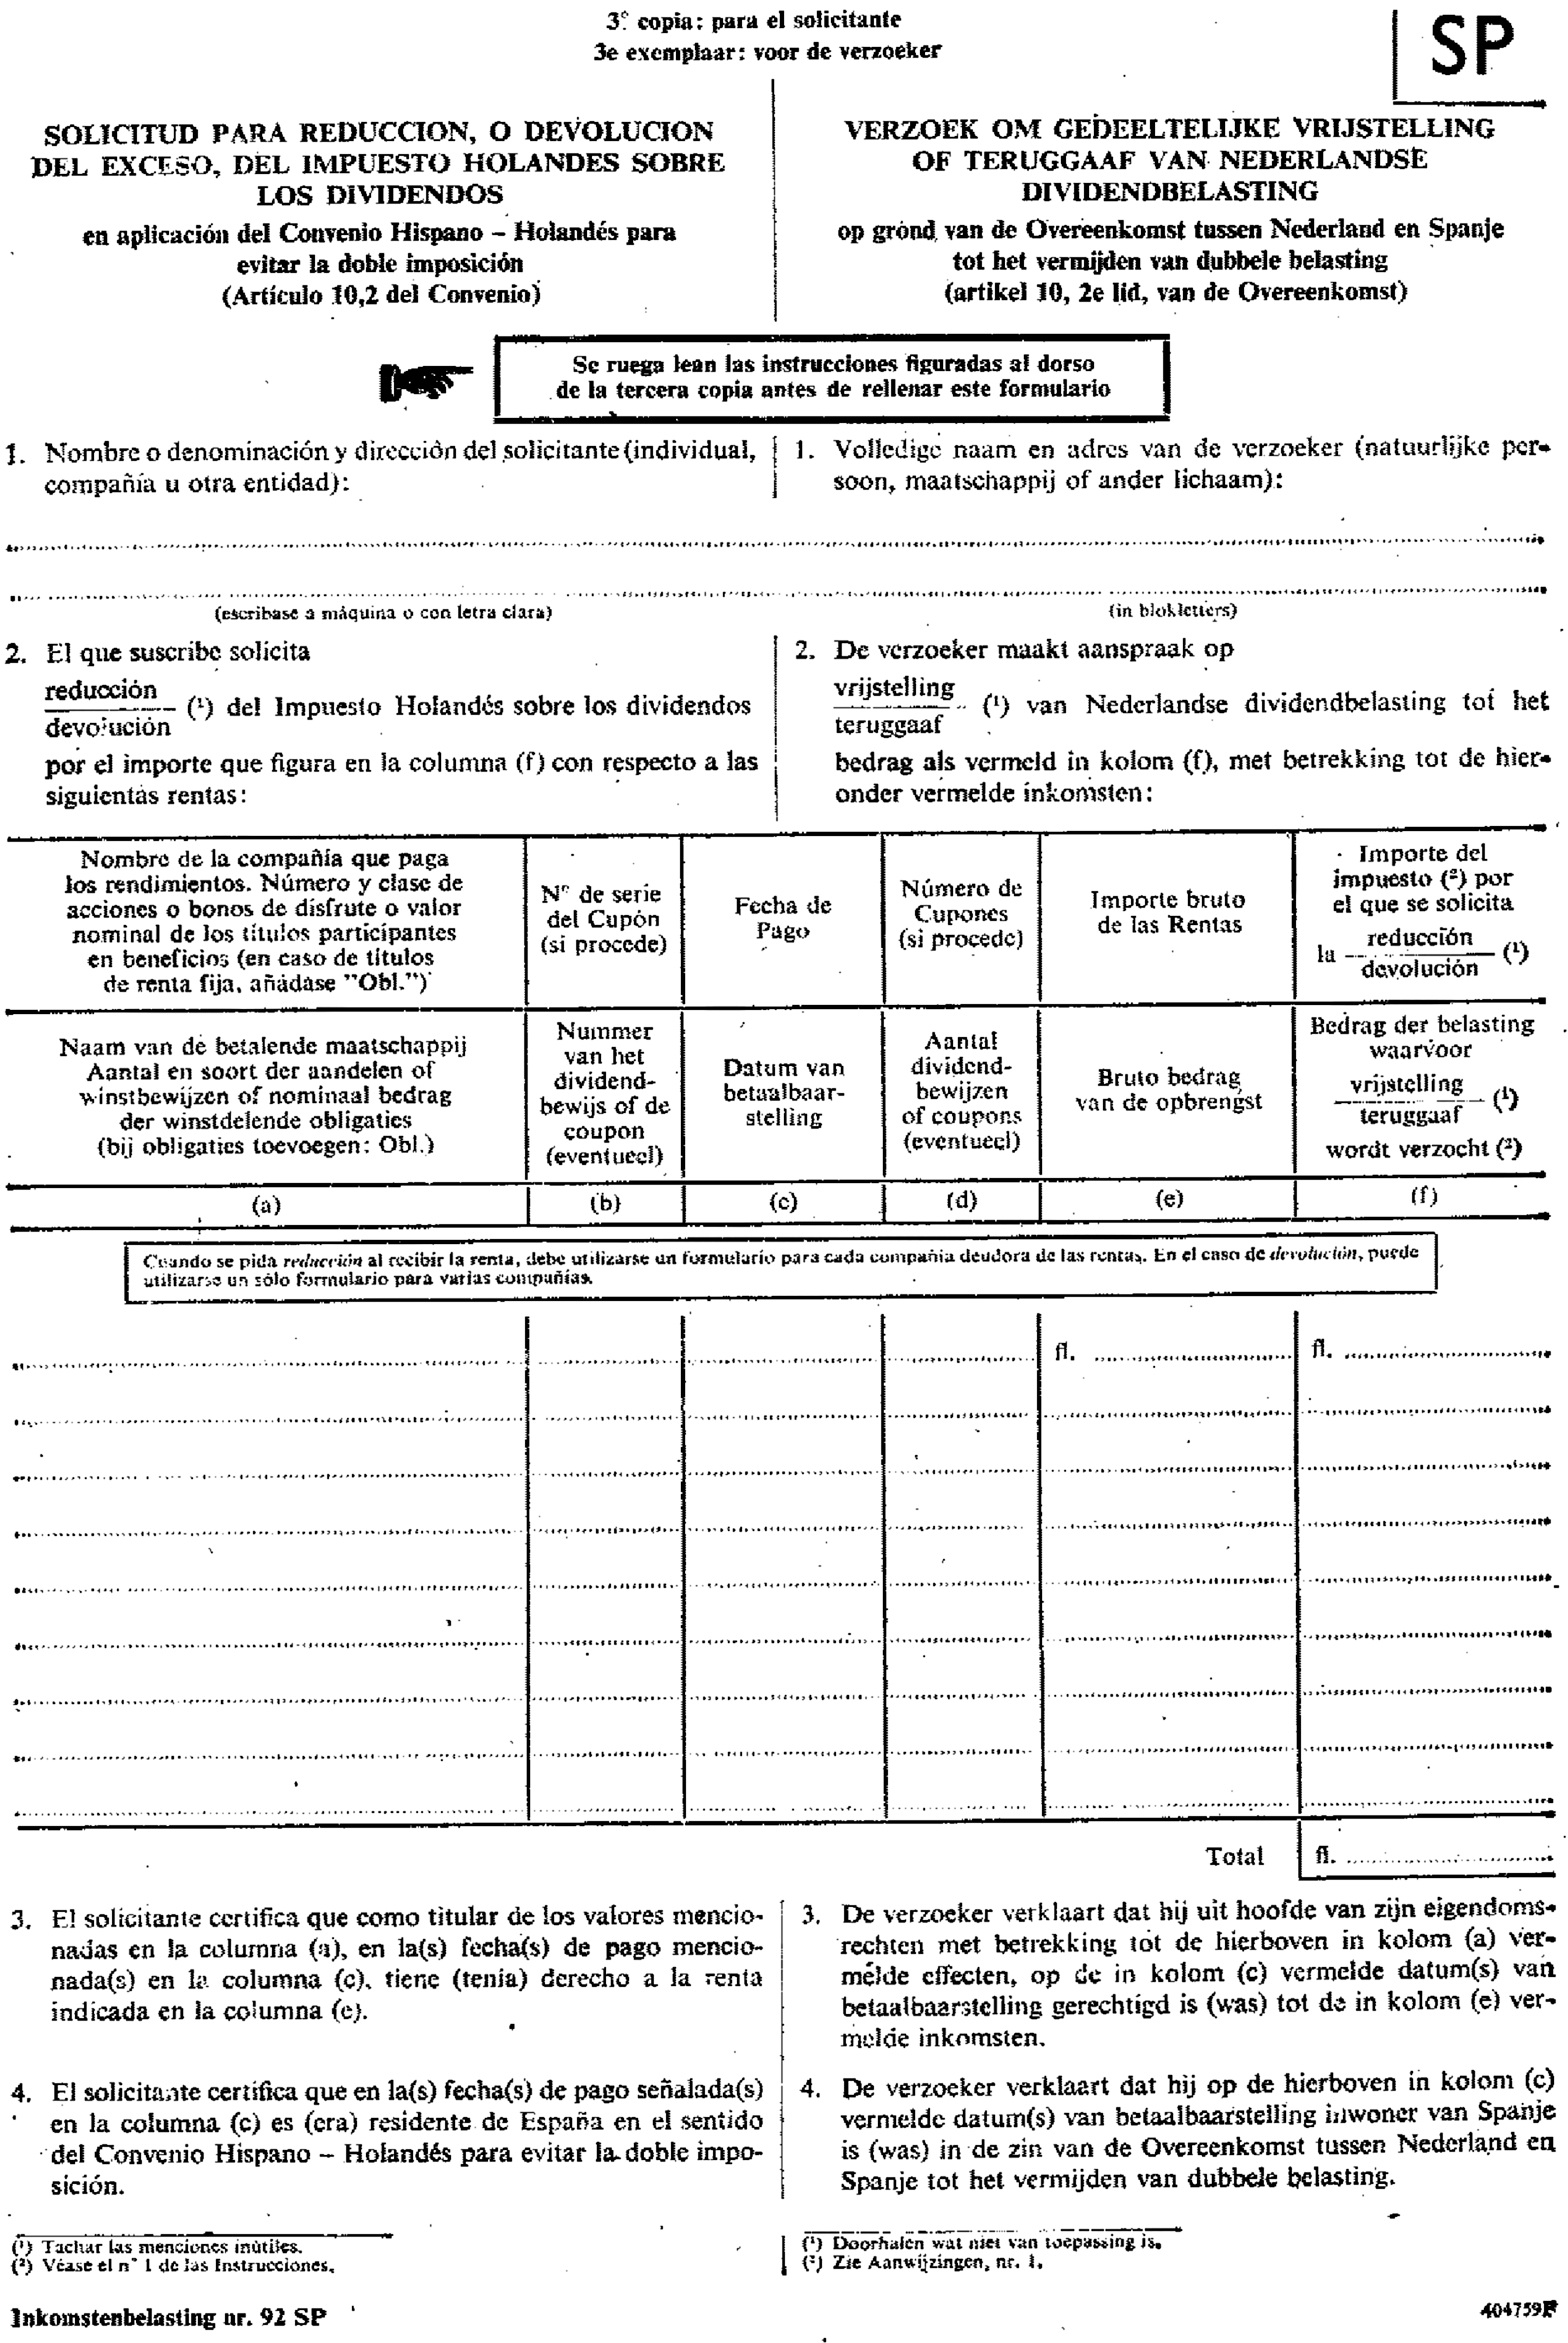
Third copy: for the applicant.
REQUEST FOR THE REDUCTION, OR RETURN OF EXCESS, OF THE HOLANDS TAX ON DIVIDENCE under the Hispano-Dutch Convention to Prevent Double Taxation (Article 10.2 of the Convention)
REQUEST FOR PARTIAL EXEMPTION FROM OR REFUND OF NETHERLANDS DIVIDEND TAX under the convention between the Netherlands and Spain for the avoidance of double taxation.
(artikel 30, 2e lid, van de Overeenkomst)
Please read the instructions on the back of the third copy before filling out this form.
1. Name and address of applicant (individual, j 1.
Company or other entity:
To be described by typewriter or with a clear letter) . The undersigned request a reduction Qe —— (2 of the Dutch dividend tax on the amount shown in column (f) in respect of the following income!
Full name and address of the applicant (individual, company or other body):
tin braklcuers)
. De verzoeker maakt aanspraak op
Exemption from or refund of Netherlands dividend tax, up to the amount shown in column (f), in respect of the [source form fragment continues; other OCR characters are unclear].
onder verdilde inrfomsten:
Name of the paying company - Amount of returns. Number and class of " A Tax number (E) for shares or enjoyment bonds or value ne Date of Coupons Gross amount which is requested nominally of the participating titles Gi rocedo) Payment (if applicable) of Incomes reduction
in profit (in the case of sp” to O and
For fixed-income securities, add “Bond”. Refund; number and type of shares; number; payment date; dividend; amount of tax. [Other form labels are unclear in the source OCR.]
Profit-participation certificates or nominal amount; payment; exemption. [Other column labels are unclear in the source OCR.]
Bonds; coupon; payment; refund amount; for bonds, add “Bond”. [Other column labels and form characters are unclear in the source OCR.]
When a reduction is requested upon receipt of the seat, a form should be used to use a single form for several connections.
to each company that owes the runs. In the dervdution house, I pusde
arevrcate
3. The applicant certifies that, as owner of the securities listed in column (a), on the payment date(s) listed in column (c), the applicant is or was entitled to the income shown in column (e). 4. The applicant certifies that, on those payment date(s), the applicant is or was a resident of Spain within the meaning of the Spain–Netherlands double taxation convention. Delete whichever alternatives do not apply. See the instructions [instruction number unclear in the OCR].
Inkomstenbelasting ur. 92 SP
400759
Original source facsimile
English rendering of a scanned annex (unverified OCR). The original facsimile is retained below for comparison.
Automatic English OCR transcription (unreviewed)
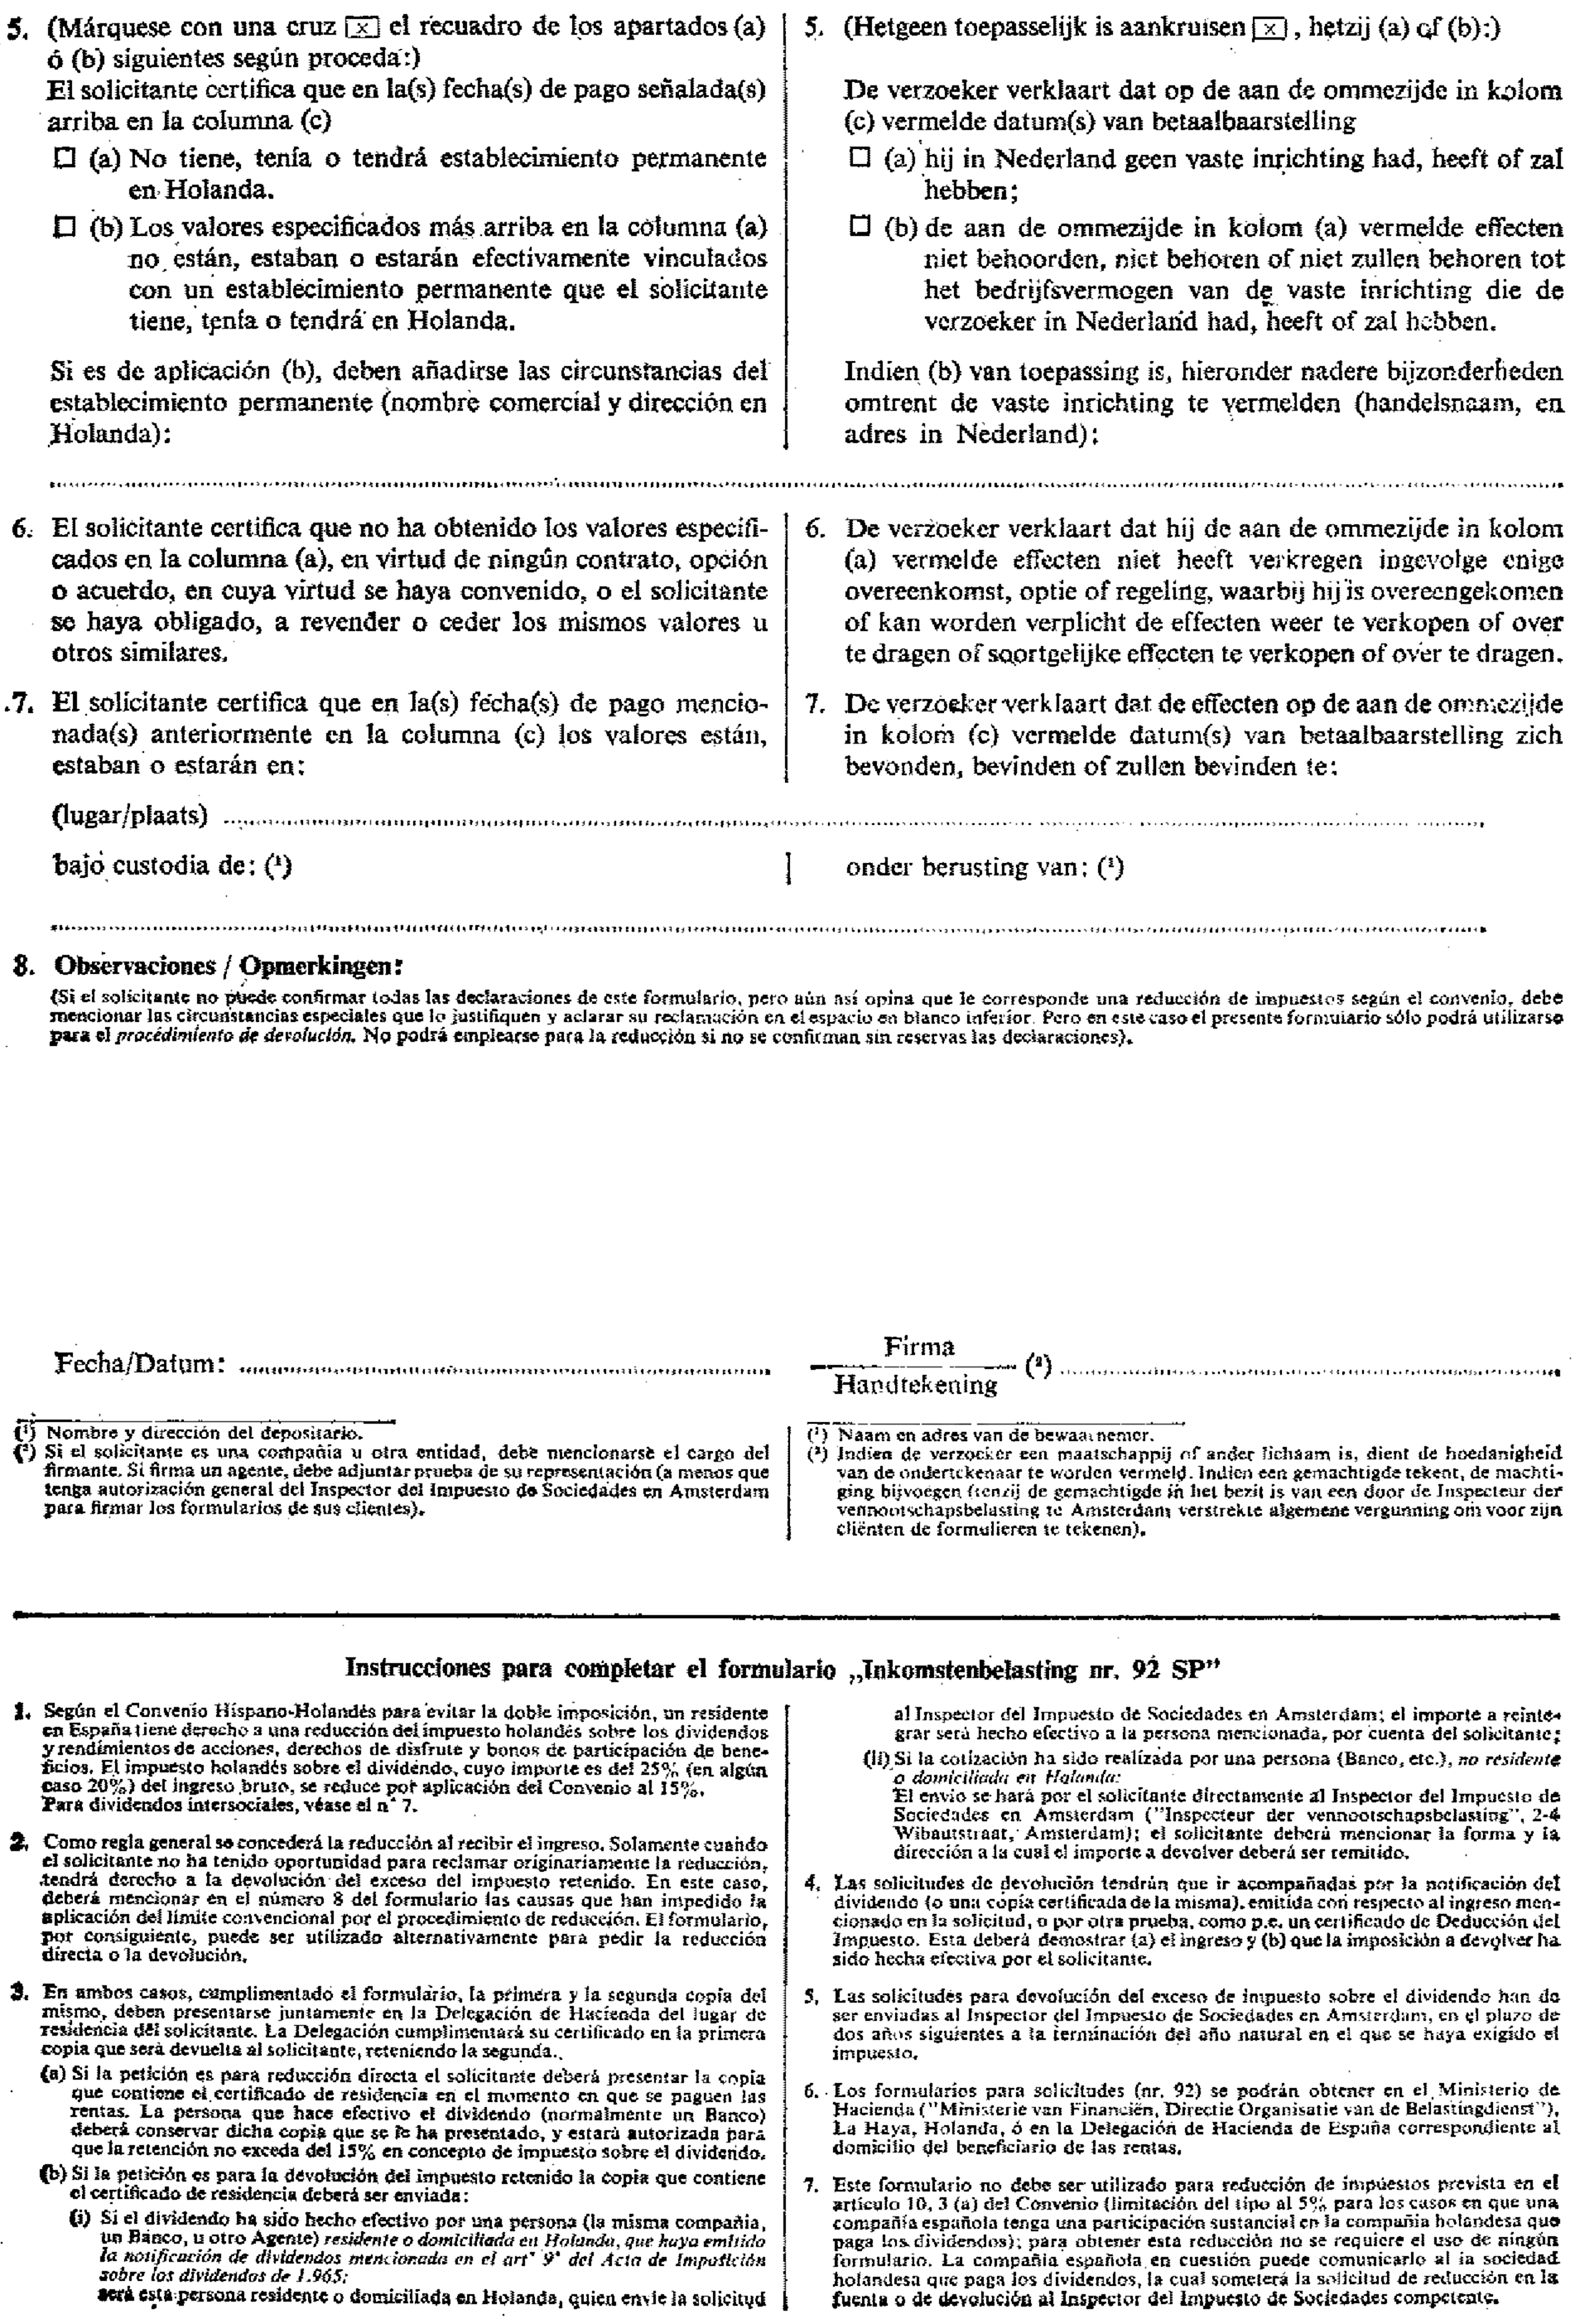
5, (Move with a cross (7 the box in paragraphs (a))
or (b) as appropriate:)
Fl applicant certifies that on the specified payment date(s)
up in column (c)
Fl (a) It does not have, had or will have a permanent establishment in Holland. :
T (b) The values specified above in column (a) are not, were or will indeed be linked to a permanent establishment that the applicant has, had or will have in the Netherlands.
If applicable (b), the circumstances of the permanent establishment (trade name and address in Bolanda) should be added:
6. The applicant certifies that it has not obtained the values specified in column (a), under any contract, option or failure, by virtue of which it has been agreed, or the applicant has been obliged, to resell or assign the same or similar securities,
7, The applicant certifies that on the date(s) of payment mentioned above in column (c) the securities are, were or will be in:
CORA OO ALI RAR RS GARA RE PARRA RADA DA DIN VDD RR RA NONI ROI LA ARRRRARA VE NIP DIO AD PR NV OR RCA PR ARES UCR A NAAA UVA LAN GASA CO GAIA NANA AGR RA AGRA THAT PAY DBA AREA ION ERR ERES ERES EA rdndo ane thin
5. Tick whichever applies, either (a) or (b).
The applicant declares that, in the column overleaf [source fragment continues].
fc) vermelde datum(s) van betaalbaarsiciling
(a) The applicant did not, does not or will not have a permanent establishment in the Netherlands;
(b) The securities listed in column (a) overleaf did not, do not or will not form part of the business assets of the permanent establishment which the applicant had, has or will have in the Netherlands.
If (b) applies, provide details of the permanent establishment below, including its trade name and address in the Netherlands:
6. The applicant declares that the securities listed in column (a) overleaf were not acquired under any agreement, option or arrangement under which the applicant has agreed, or may be required, to resell or transfer those securities or to sell or transfer similar securities.
The applicant declares that, on the payment date(s) shown in column (c) overleaf, the securities were, are or will be located at: [blank].
Qugar/plaatS)
in the custody of: (1)
Ibbana ro ro ro ros error ra roses,
$. Observations / Opmerkingen!
(If the applicant fails to confirm all declarations)
de cste fl dl
onder berusting van; (3)
ARA AR RIIIE AN TIRRA RARA OR RIA RRIEN RATO ERE D ANNA AGO ROPO SRA GER RC ENS AA TAS AGO Cr bbbrroooa devanoosa AS ERAS
but still thinks that it is due a reduction of taxes according to the agreement, it must
spond to the special circumstances justifying it and clarify its reclaration in the lower blank space. But in this vessel this form may only be used for the return procedure, It may not be used for the reduction if the declarations are not unreservedly contained).
Date/DataM! snoring
(1) Name and address of the depositary.
€) If the applicant is a company or other entity, mention must be made of the position of the signatory, If you make an agent, you must attach proof of its representation (unless you have general authorization from the Company Tax Inspector in Amsterdam to copy the forms of your customers).
ARRE SERES]
Handtekening
() Naam en adres van de bewaanencr.
(2) If the applicant is a company or another body, the capacity of the signatory must be stated. If a representative signs, attach the authorisation, unless the representative holds a general authorisation issued by the Inspector of Corporation Tax in Amsterdam to sign forms on behalf of clients.
Instructions to complete the form ,Tnkomstenbelasting nr, 92 SP”
3. According to the Spanish-Dutch Agreement for the Prevention of Double Taxation, a resident of Spain is entitled to a reduction in the Dutch tax on dividends and income from shares, rights of enjoyment and bonds of participation of bene’, Eli Dutch on the split, the amount of which is 259; in some £aso 20%) of the gross income, is reduced the application of the Agreement to 15%, Pará dividendes intersociales, see n* 7.
2, Coro general rule ss will grant the reduction upon receipt of the income. Only when the applicant has not originally had the opportunity to claim the reduction will he be entitled to refund the excess of the tax withheld. In this case, the cases which have prevented the application of the conventional limit by the drafting procedure must be r 3 in the 8th year of the fitario. The form may therefore be used alternatively to request direct reduction or refund,
3. In both cases, the form, the first and second copies of the nism, must be submitted together to the Treasury Delegation of the requesting place of residence dll. The Delegation completes its certificate in the first copy that will be returned to the applicant, retaining the second. £e) If the request "is for direct reduction the applicant must submit the enpia
ü contains a residence certificate at the time when the
rents. The person making the dividend (usually a bank) must keep the copy that has been submitted, and it shall be authorised to retain the dividend tax not exceeding 15 per cent;
€b) If the request is for the refund of the tax withheld the copy containing the certificate of residence must be sent:
(6) If the dividend has been made effective by a persone (the same company, a Bianco, another Agent) resident or domiciled eu Holland, which kuya issued gives notice of dividends referred to in Article 9" of the Imputltion Act on dividends of 1,965;
You will be resident or domiciled in Holland, who sends the request
to the Company Tax Inspector in Amsterdam; the refund amount. £rar shall be paid to the person concerned on behalf of the applicant; (19 If the contribution has been revoked by a person (Banco, ete), non-resident 0 domiciled in Palamde: The shipment shall be made by the applicant directly 21 Inspector of the Company Tax in Amsterdam ("Inspocteur der vennootschapsbelasting", 2-4 Wibautstraat,' Amsterdam); the applicant shall mention the form and address to the cusl the amount to be returned shall be forwarded,
4. Requests for repayment must be accompanied by the dividend statement (or a certified copy thereof) issued in respect of the income referred to in the request, or by other evidence, such as a tax deduction certificate. This must establish (a) the income and (b) that the tax for which repayment is requested has actually been paid by the applicant.
S, applications for the refund of excess tax on the dividend must be sent to the Company Tax Inspector in Amsterdam within two years of the date on which the tax was imposed,
6.-Applications forms (nr, 92) may be obtained from the Ministry of Finance ("Ministry of Finance van Financiero, Directie Organisatie van de Belastingdicast), The Hague, Holland, 9 from the corresponding Delegation of Finance of Espuña ul address of the beneficiary of the rents,
7. This form should not be used for the reduction of charges provided for in Article 10, 3 (4) of the Agreement (imitation of the type to 59, in cases where a Spanish company has a substantial participation in the Dutch company that pays the dividends); to obtain this reduction the use of any form is not regulated, the Spanish company in question can inform the Dutch company that pays dividends, which will submit the request for reduction in the fuente or of return to the Tax Inspector of Companies Compel.
Original source facsimile
ANNEX No 2
English rendering of a scanned annex (unverified OCR). The original facsimile is retained below for comparison.
Automatic English OCR transcription (unreviewed)
Example 1 for the Adminis.
EE-RPB
REDUCTION REQUEST
of the Spanish income tax covered by Articles 10 and 11 of the Agreement between Spain and the Kingdom of the Netherlands of 16 June 1971
Name and name (1) or business name of the owner (2) of the securities
Addresse complita 20. sto
The undersigned certifies that the owner 12) usufructaire (2) of the titles designated for continuation:
»w Has the status of resident of the Netherlands within the meaning of the Spanish-Dutch Tax Agreement.
— does not have permanent ownership of the cul in Spain is effectively linked to the participation and the crádita genaradores of the incomes in question, and asks for the reduction of the Spanish imp corresponding to the incomes listed below of the titles erected by 13) IPC RO PARO VEA IP RRA ca AM ar rra arenas ero boleas prisoners horroso ero .. Pormeara and Pere. .pe. rOhA to challenge ebro Lil
Number of the unit value - Total value Date of ] Number of number of serial date of f Number of ⁇ - 5, Nature of these titles 14) edchisíció am de toa eel maturidad - jriodebcupón] tool, Fxpor wanted tulos os titles coupons: , : from coupons to cabbage. Q) A E E Bb E F G H Total in pesetas coupons tmp 5 deduci . for $00 16) A Dividend or interos net msremmorsorso]
Name, quality and say dal rapr Made sn a
coma. a.
Signature of the owner (2) user (2) or his representative to
(1) Underline the last name(s).
(2) Tachbar all useless indications,
(3) Name and address of the community to Spanish-based broadcasting company (or debtor of interest).
(4) In the case of interest on loans, these last terms are not represented by obligations; this circumstance shall be indicated in Cos tumna A. In column B, the date on which the loan was contracted shall be indicated, and in column E, the 5 amount of interest for which the tax reduction is requested. The remaining Columns will be left blank.
(5) If the shares do not bear coupons, the final payment of the dividends shall be indicated in column E and in column 6, the amount of this dividend per action,
(6) Appropriation of the conventional rate and the amount a of the Spanish tax which is retained at the source in accordance with Articles 10 and 2 of the Convention,
Original source facsimile
English rendering of a scanned annex (unverified OCR). The original facsimile is retained below for comparison.
Automatic English OCR transcription (unreviewed)
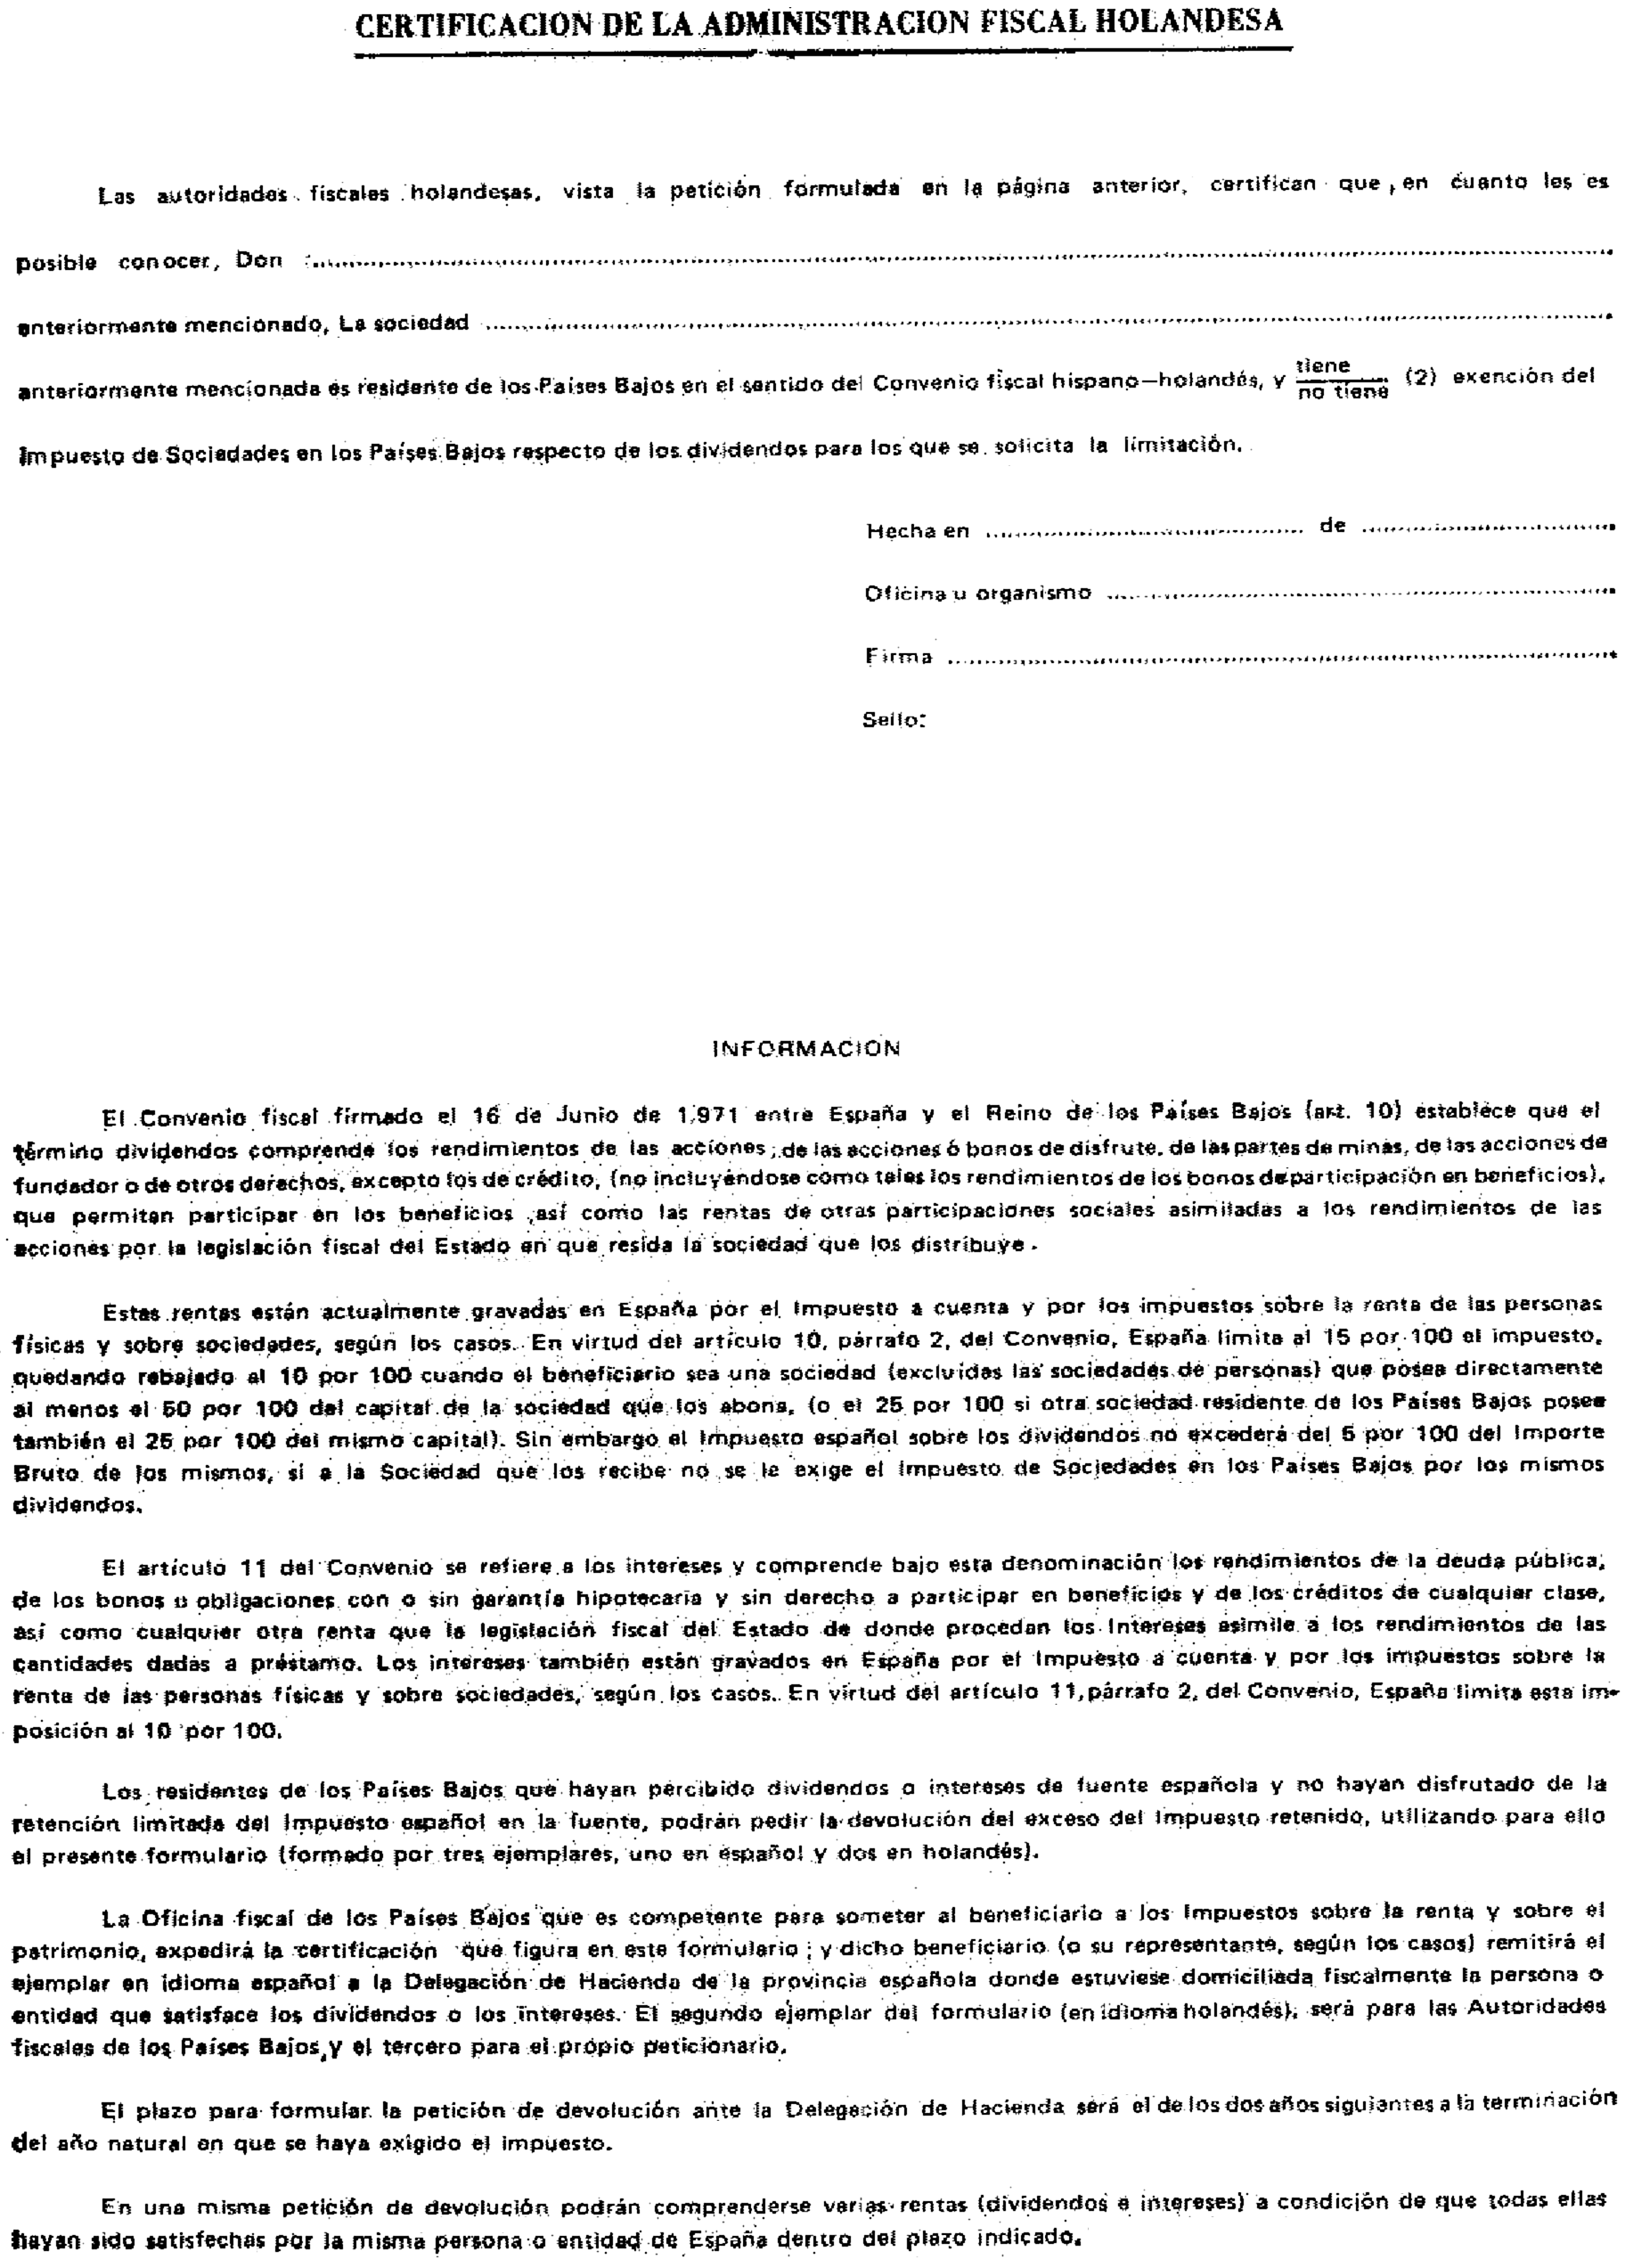
CERTIFICATION OF HONEY TAX ADMINISTRATION
The Dutch territorial utorities, having regard to the request made on the previous page, certify qua, as soon as it is possible to know, DON enesernartorca reno coran sarezoer Von 108 FR IR LN ADD AA FDO DF RAN RIOS DD GRS LABFR RAE DIDDEG GRIND ODA DUDEBSI DIO IOO0 AGAR NED ARIADTEDESAFO VOB RARDA ROAD ORBE OR REN FAP ervamr minor 0070
The company referred to above [blank; the remaining form text is unreadable in the source OCR].
Referenced above by the Netherlands within the meaning of the Spanish-Holendese Tax Convention, and AA (2) exemption from
corporation tax in the Netherlands in respect of dividends for which the limitation is requested,
80 pocmsrasroscrcrrmerriarnra Or carrer in err start
Office & OTYANIBNMO eocirocisororaccorrosacrosariconcccriarnecasar armernerarre a Firma omos » A. Salio;
INFORMATION
The Tax Convanio. signed on 16 June 1971 between Spain and the Kingdom of the Netherlands Palses far. 10) provides that (e) the term dividends includes the income from shares of shares in shares or bonds of enjoyment. of the shares of mines, of the shares of founders or of other rights, except those decrédito, (not included as such. the returns of the bonds of participation in profits), which allow to participate in the profits, so as to eat the rents of other social participations assimilated to the returns of the Shares by the fiscal legislation of the State in which the company that s0s disstrubuys resides,
These rents are currently taxed in Spain by account tax and income taxes on natural persons and companies, as the case may be. By virtue of Article 10(2) of the Convention, Spain limits the tax to 15 per 100, which is reduced to 10 per 100 the beneficiary is a company lexcluidos companies of persons) holding directly at least 50 per 100 of the capital of the company that pays them; 25 per 100 the other company resident in the Netherlands also 25 per 100 of the same capital). However, the Spanish dividend tax shall not exceed 5 per cent of the gross income of the dividends, i.e. the company which the companies do not require the corporation tax in the Netherlands for the same dividends,
Article 11 of the Convention refers to interest and includes under this heading the income from public debt, bonds or bonds, with or without mortgage guarantee and without the right to participate in profits and credits of any kind, as well as any other income from the tax legislation of the State from which the income from the amounts lent is derived. Interest is also taxed in Spain by the tax on account and taxes on the fonta of natural persons and on companies, depending on the case. Under article 11, paragraph 2, of the Convention, Spain limits this 10 per 100 position,
Residents of the Netherlands who are to receive dividends and contributions from Spanish sources may apply to the Spanish tax authorities for the application of the Jimitedo tax in accordance with Articles 10 and 11, paragraph 2, of the Convention, for which purpose they must complete this questionnaire (made up of two copies in Spanish and two in Dutch).
The Federal Office of the Netherlands, which is competent to subject the beneficiary to income and property taxes, shall issue the certificate set out in this form; and that beneficiary shall send the two copies in the Spanish language to the resident entity of Spain which is liable to pay the said income. This persora or entity will accompany one of the copies to declaration-liquidation that must be submitted to the Delegation of Finance
(N9 1), The second copy in the Espalto language! (NO 3) shall be kept for record by the person or entity that is resident in Spain. Ñ
A copy of the questionnaire in the Dutch language shall be held by the beneficiary of the interest dividends (N? ay elotra sorá for the Figoal Administration of the Netherlands (NO 2) to the corresponding effects.
Original source facsimile
ANNEX No 3
English rendering of a scanned annex (unverified OCR). The original facsimile is retained below for comparison.
Automatic English OCR transcription (unreviewed)
Example 1 for the Adminis-EE-RPB
of the Agreement between Spain and the Kingdom of the Netherlands of 16 June 1971
Name and applications (1) or business name of the owner (2) usutfructuary (2) of two RIOS nnmnar II IR
EEA IT TO IIA ON ERA PARAN RAN AVTN VA DA DR DIEDI AGP LROS ORGIA YOUR NO RO TREN APPURE RAP ABACO CAES AGRA R IDO OREA DERIITOI ENDE RIZRO ARI AR GVAN IRIS R ERC AE rIna
Address SOMPIETA rmmntar rara ets 9023003000 A NAPA TACA R ASI RAI LENA GRUA IAE NERAL LATAS DABA OIR RAR I OLA TAR RIA DINAR EII EI IAE SI BRIEVA GEA PRI .....
The undersigned certifies that the owner (2) usufructaire (2) of the following titles: — has the status of resident of the Netherlands within the meaning of the Dutch Spanish Tax Convention. + does not have in Spain a permanent establishment to which parsicipation 9 is effectively linked the credit generated by the
and asks for the refund of the excess of the Spanish tax satisfied and corresponding to the revenues listed A contiso
Securities issued by [blank; the remaining form text is unclear in the source OCR].
ROA TA A IR
Number of se- Value units- Total value, Date of Number of ⁇ Serial number] rieodate def Number of f . . 2 nn. or river of Tcol coupon. FE. by Nature of the securities (4) title title title maturity 10H quis - titles and titles ⁇ , coupon coupons ptas, (5) col. 6) A B £ [2] E F G n Total of Total in possessive coupons Tax retained at source 2.0... 0.10... JO) j rra nna ro rra ra ra rano frog naa pesetas (7) Convention limit ..ocornon=ooroconcr<o QS) dranoncr norra rra rr rrn pesetas (9) Quantity to be returned (difference between lines (7) and 19 drenreconcracorncarncro faces PESOtAS
Number and date of the document attesting (letter of payment) if tax has been paid to the tax the refund of which is requested in respect of the excess (10) ..conarorncnr rr rr A
Spoñol bank or operator in Spain appointed by the person concerned to pay the refund requested for his or her own account and on his or her behalf 111) : 22’.
Name, quality and direction of the empowered Made in. or nar narrate Bl rra rem
rr nana rr r r r r r r r r s A
Signature of the owner (2) usufructaire (2) or his proxy 12)
PEPE AAA
(4) Underline the last name(s).
(2) Tacbar all useless indications, Ñ
(3) Name and address of the collectivity or broadcasting company resident in Spain (0 of the interest rate),
(4) In the case of interest on loans not represented by obligations, this circumstance shall be indicated. In Columma B., the date on which the loan was contracted and in column M, the amount of interest for the cuqs shall be indicated.
It calls for the return of the excess tax. The remaining columns will be left blank.
(5) If the actions do not carry coupons, the amount of this dividend per share shall be entered in column E.
(6) Indicate the percentage.
(7) Indicate the total tax withheld at source:
(8) Indicate the percentage limit in accordance with Articles 10 and 11, paragraph 2, of the Convention,
(9) Enact the total tax corresponding to the application of the limits set out in Articles 10 and 11. paragraph 2, Bel "Convent,
(10) If the data subject uses this information, he or she shall, if he or she ignores the data subject, issue a comprehensive certificate of the date and number of the document proving the income of the tax, to the person or entity resident in Spain who is willing to pay the dividends or interest. In the event that the certificate is not presented together with this form, the refund of the excess tax shall also be processed when the information indicated is produced by the Treasury delegation.
(11) If the beneficiary of the refund of the excess tax withheld at the source wishes to designate a person or entity resident in Spain other than a Bank, in order to obtain cash the amount of the said excess, it shall be so stated in the form, indicating the names and surnames or business name, name, ac. of that person or entity, as well as the place and address of his tax domicile in: Spain,
Original source facsimile
English rendering of a scanned annex (unverified OCR). The original facsimile is retained below for comparison.
Automatic English OCR transcription (unreviewed)
CERTIFICATION OF HONEY TAX ADMINISTRATION
The authorities. Dutch prosecutors, having regard to the request made on the previous page, certify that, in cdugento
possible to meet, Don
The above mentioned partnership , .ncircccrncnnno nor cr sea acre prono Lor rmrtran ero iro ten rarcongoro ... és resident of the Netherlands within the meaning of the Spanish-Dutch Tax Convention, and A (2) exemption from Company Tax in the Countries. Netherlands for the dividends for which the request is made.
Made BP rmicrorrorncnrr of .
Dticin to ORganisMO cr
EMMA rocroror nooo rre rare errors erre
Seilo:
INFRAMATION
The tax convention signed on 16 June 1997 between Spain and the Kingdom of the Netherlands (art. 10) states that the term dividends includes the earnings of the actions; “of the shares 6 enjoyment bonds, of the parres of mines, of the shares of founders or of other rights, except credit fos, (not including as teles the returns of the bonds of participation in profits), which allow to share in the profits thus I share the income of other social participations assimilated to 108 returns of the “sections by. the tax legislation of the State in which the company in which they reside -
These income is currently taxed in Spain by the account tax and income taxes of individuals and companies, as the case may be. Under article 10, paragraph 2, of the Convention, Spain limits the tax to 15 per 100 per cent. Remaining reduced to 10 percent when the beneficiary is a society fexcluidas laz sociedadás.de people? “that you own directly at least 50 per cent of the capital of the company aue.los pays it, 25 per 190 if another company. resident of the Netherlands also poses 25 per +00 of the same capital). However, the Spanish tax on gSividendos.does not amount to $ per 100 of the Gross Amount of the same, if and the society that receives them: no. you are required to tax. of Companies in the Netherlands for the same dividends.
Article 11 of the Agreement refers to interest and comprises under this heading the income from public debt, bonds and bonds. It is similar to the yields of the Amounts given on loan. Intarese are also taxed in Spain by ef Impuesto to “account. and by taxes on the income of individuals and on sotiéties, according to the cases. By virtue of Article 11, paragraph 2, of the Convention, Spain limits this Ime position to 1H "per 100,
Residents of the Netherlands who have lost dividends to interest of Spanish source and have not enjoyed the limited Tittention of the Spanish tax in the Tuente, may request the return of the excess of the tax withheld, Using for this purpose to this form it is formed by three copies, one in Spain! and two in Dutch).
The Dutch Tax Office “who is competent to submit to the beneciary: Jos Tax on income and on property, shall issue the certificate contained in this form : and the beneficiary. (or his representative, as the case may be) shall send the copy in Spanish to the Delegation: from Hacienda de Ja provincia española where the person or entity satisfying the dividends or interest was taxed. The second copy of the form (Dutch language) will be for the Tax Authorities of the Netherlands, and the third for "the petitioner,
The time limit for: to formulate. the request for refund shall be the two years following the end of the calendar year when the tax has been imposed.
In the same request of return can be understood Several: rents (dividends to inilieres) provided that they have been satisfied by Ja same person:or entity of Spain within the specified time.
Original source facsimile