DOCUMENT
Order of 4 December 1978 on the application of Articles 10, 11 and 12 of the Convention between Spain and Denmark on the avoidance of double taxation of income and property taxes of 3 July 1972.
04.12.1978 · BOE-A-1979-229
Illustrated sir:
The Convention between Spain and Denmark on the Prevention of Double Taxation of Income and Wealth Taxes was signed on 3 July 1972 and entered into force on 20 June 1973 and was published in the Official Gazette of the State of 28 January 1974. The application of some of the provisions of the Convention, such as those relating to dividends, determines the desirability of establishing, in accordance with article 10 of the treaty text, rules governing the procedure to be followed for the better effectiveness of the limits laid down in that provision; the same applies to interest and royalties, in accordance with articles 11 and 12 of that text.
The guidelines set out in the regulations of previous international conventions of the same nature are generally followed, introducing the peculiarities imposed by the specialities of the Danish tax system.
By virtue of that,
This Ministry, in agreement with the tax authority responsible for the Danish Convention, has provided for:
First. Residents of Spain.
(A) Income covered by article 10 of the Convention.
(a) Persons or entities having the status of residents of Spain, as provided for in Article 4 of the Convention, who have received dividends from a Danish source, may request the Danish tax authorities to refund the excess Danish tax retained at the source on the above-mentioned income. This excess consists of the difference between the amount of the tax quota applied in accordance with domestic law and that applicable in the light of the limits set out in Article 10 of the Convention.
The return request must be made using Form U 36 E (Annex I to this Order). This form will be provided by the Treasury Delegations in Spain.
Completed by the person or entity would benefit from the dividends the data contained in the form, it will be presented to the Treasury Delegation corresponding to its tax domicile. The International Conventions Section, or the Office which performs such functions in that Delegation, taking into account the background information contained therein and, where appropriate, the national identity card, passport or document certifying the residence, the display of which may be required, shall extend the procedure provided for in the form. The applicant shall send the relevant copies (1 and 2) to Statsskattedirektoratet, kildeskat, Box 100; DK-3460 Birkerød, Denmark; the third copy (3) shall be held by the applicant.
B) Income covered by Articles 11 and 12.
In the absence of tax retention in Denmark, there is no need to regulate an application procedure for the limits contained in such articles of the Convention.
Second. Danish residents.
(A) Income covered by articles 10 and 11 of the Convention.
(a) Dividends and interest from Spain received by persons or entities which, pursuant to Article 4 of the Convention, have the status of residents of Denmark, shall be taxed in Spain on the Income Tax of Physical Persons by withholding tax, carried out within the limits set out in Articles 10 and 11 of that text. In order for these limits to be applied, the request must be made to the Spanish tax authorities.
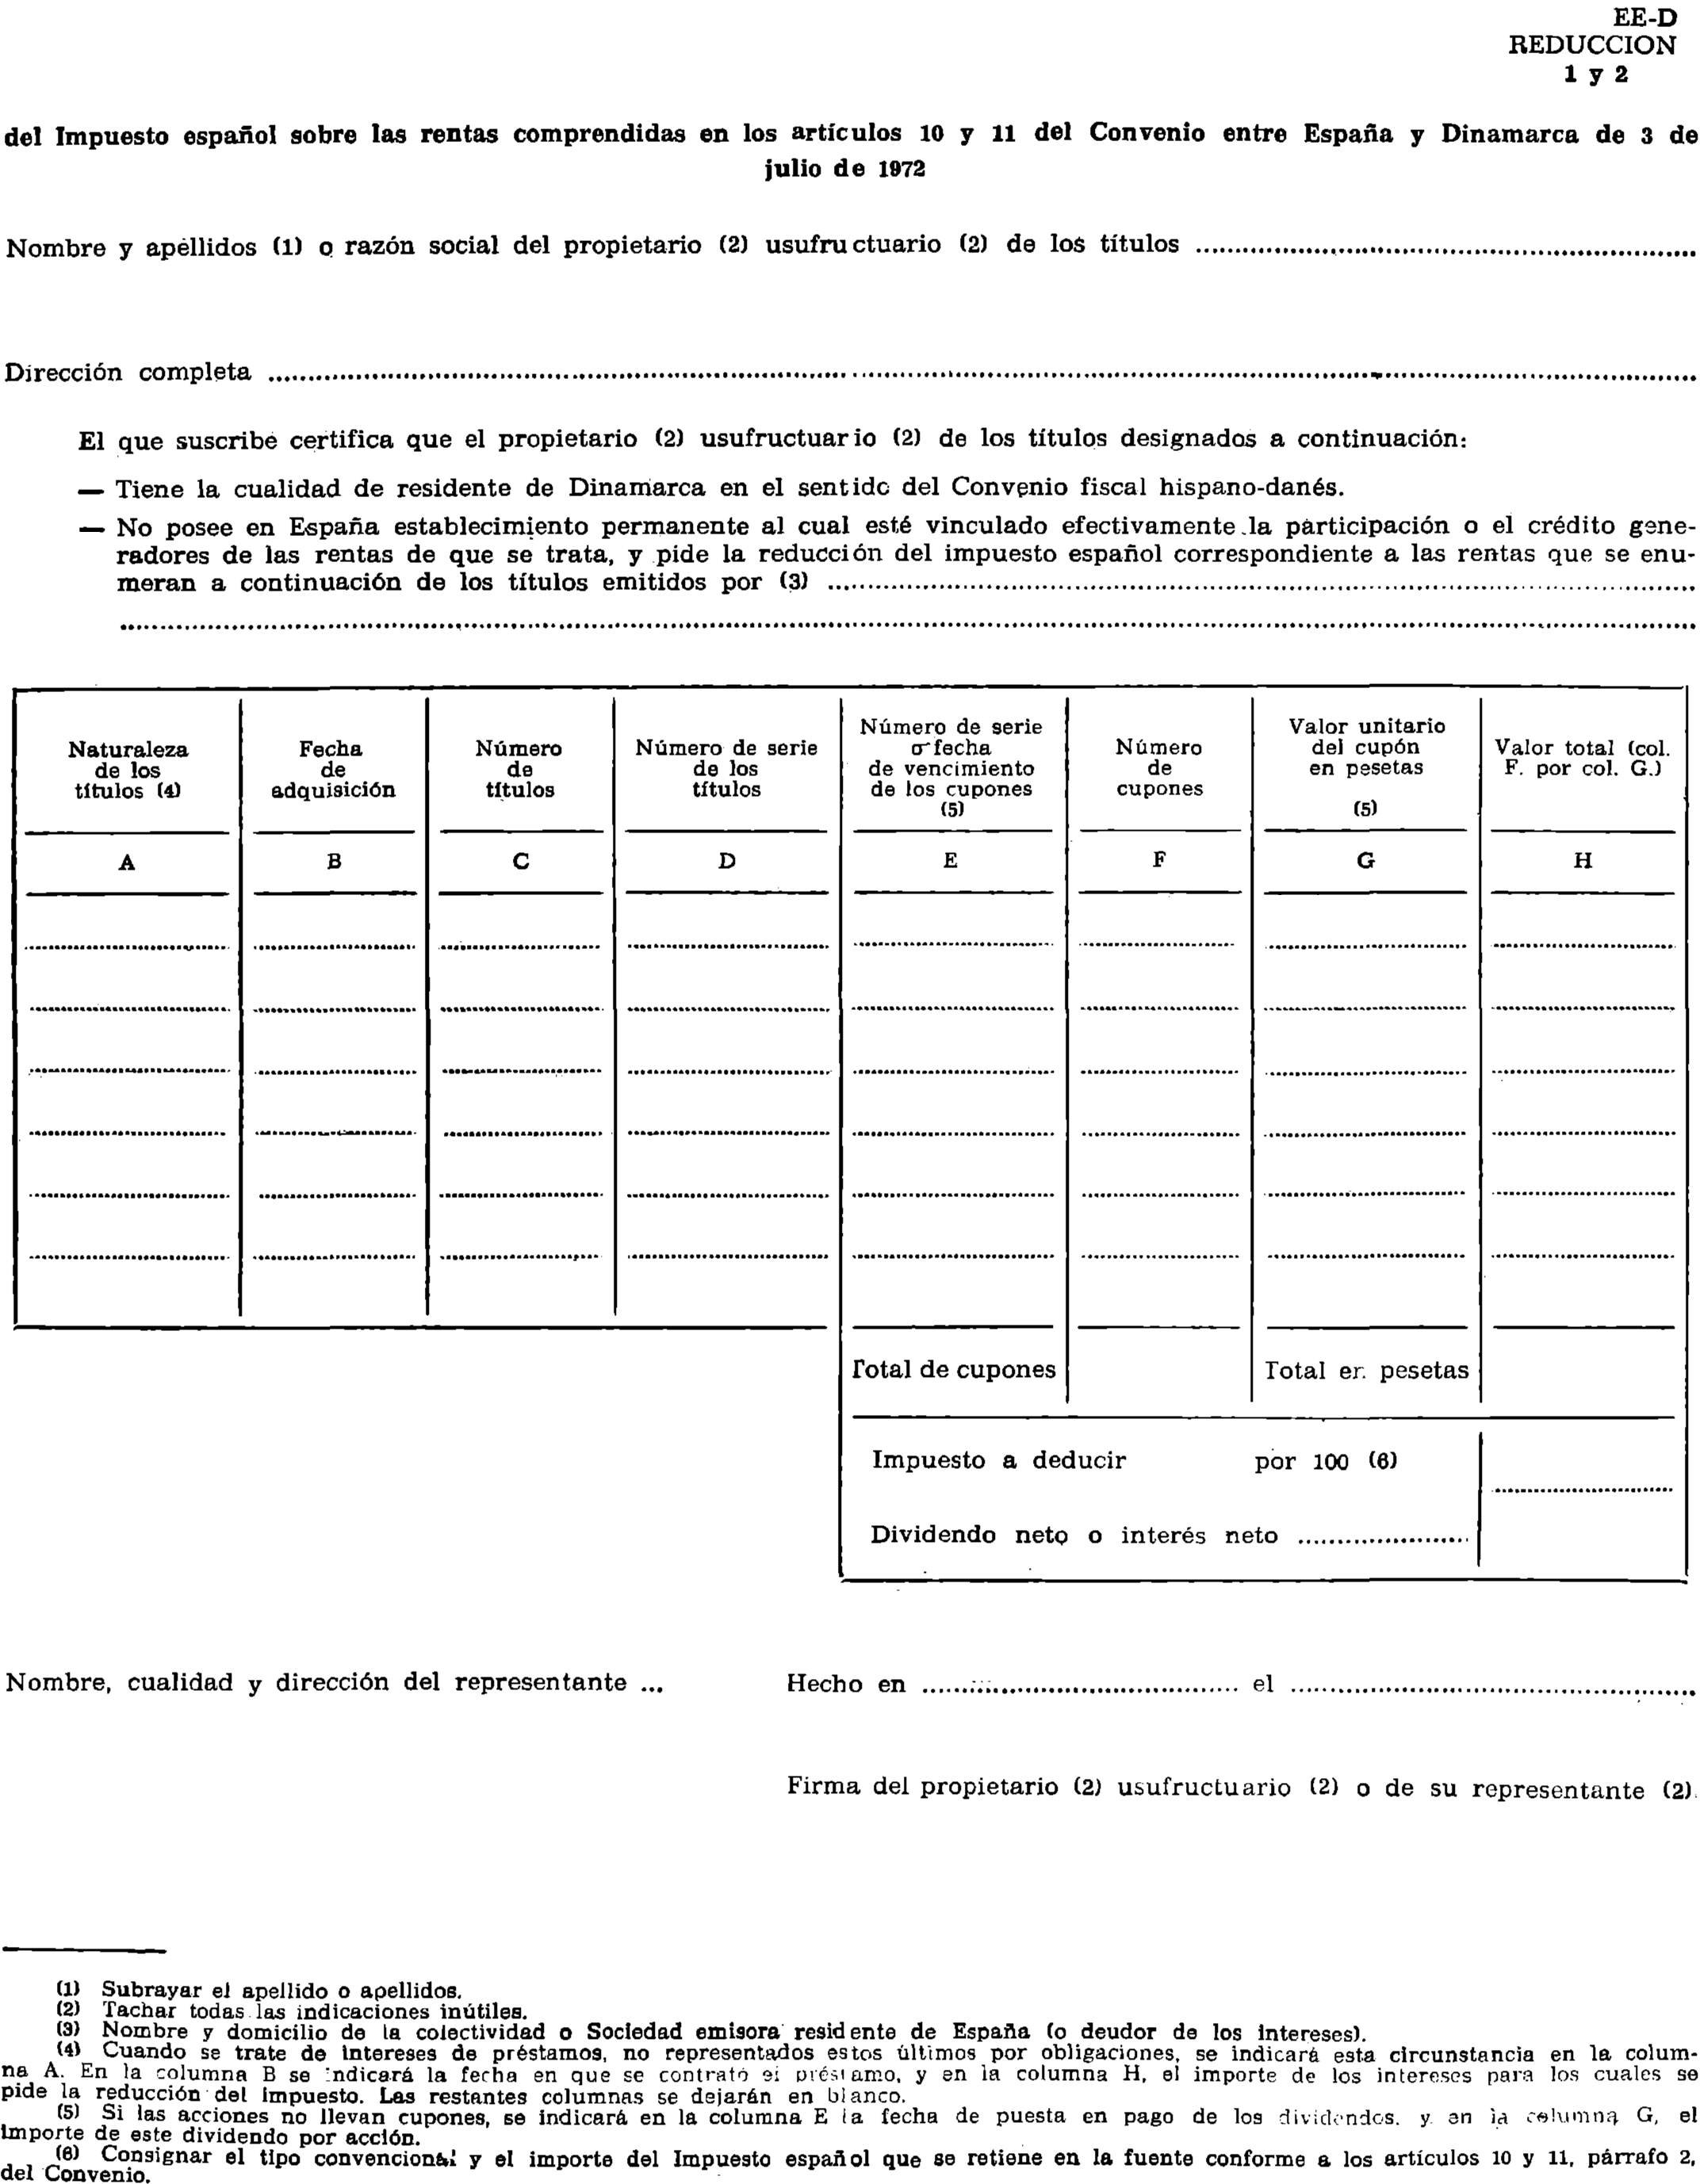
(b) The application shall necessarily be made in the model form EE-D, Reduction (Annex II to this Order), which shall be provided by the Danish tax authorities. Once the form has been completed by the beneficiary or his representative and the diligence shown therein by the competent Danish office has been extended, he shall send the two copies written in Spanish to the resident person or entity of Spain, which is responsible for the income expressed. This person or entity, when paying the dividends or interest, shall levy the Spanish Tax on the Income of Natural Persons, applying the limits of the Convention (Articles 10 and 11), and accompanying the tax settlement declaration, which it is required to submit to the corresponding Treasury delegation, one of the copies of the form, as proof that the tax withholding has been made, taking into account the conventional limit; the second copy in Spanish language shall be kept for record by the resident debtor person or entity of Spain. One copy in Danish shall be held by the payee of the dividends or interest; the other, in Danish, shall be held by the Danish tax authorities for the corresponding purposes.
(c) If the procedure of reduction has not been used and the tax has been withheld, in accordance with the rules of Spanish domestic legislation, the application of the conventional limit shall be effected by refund of the excess tax withheld.
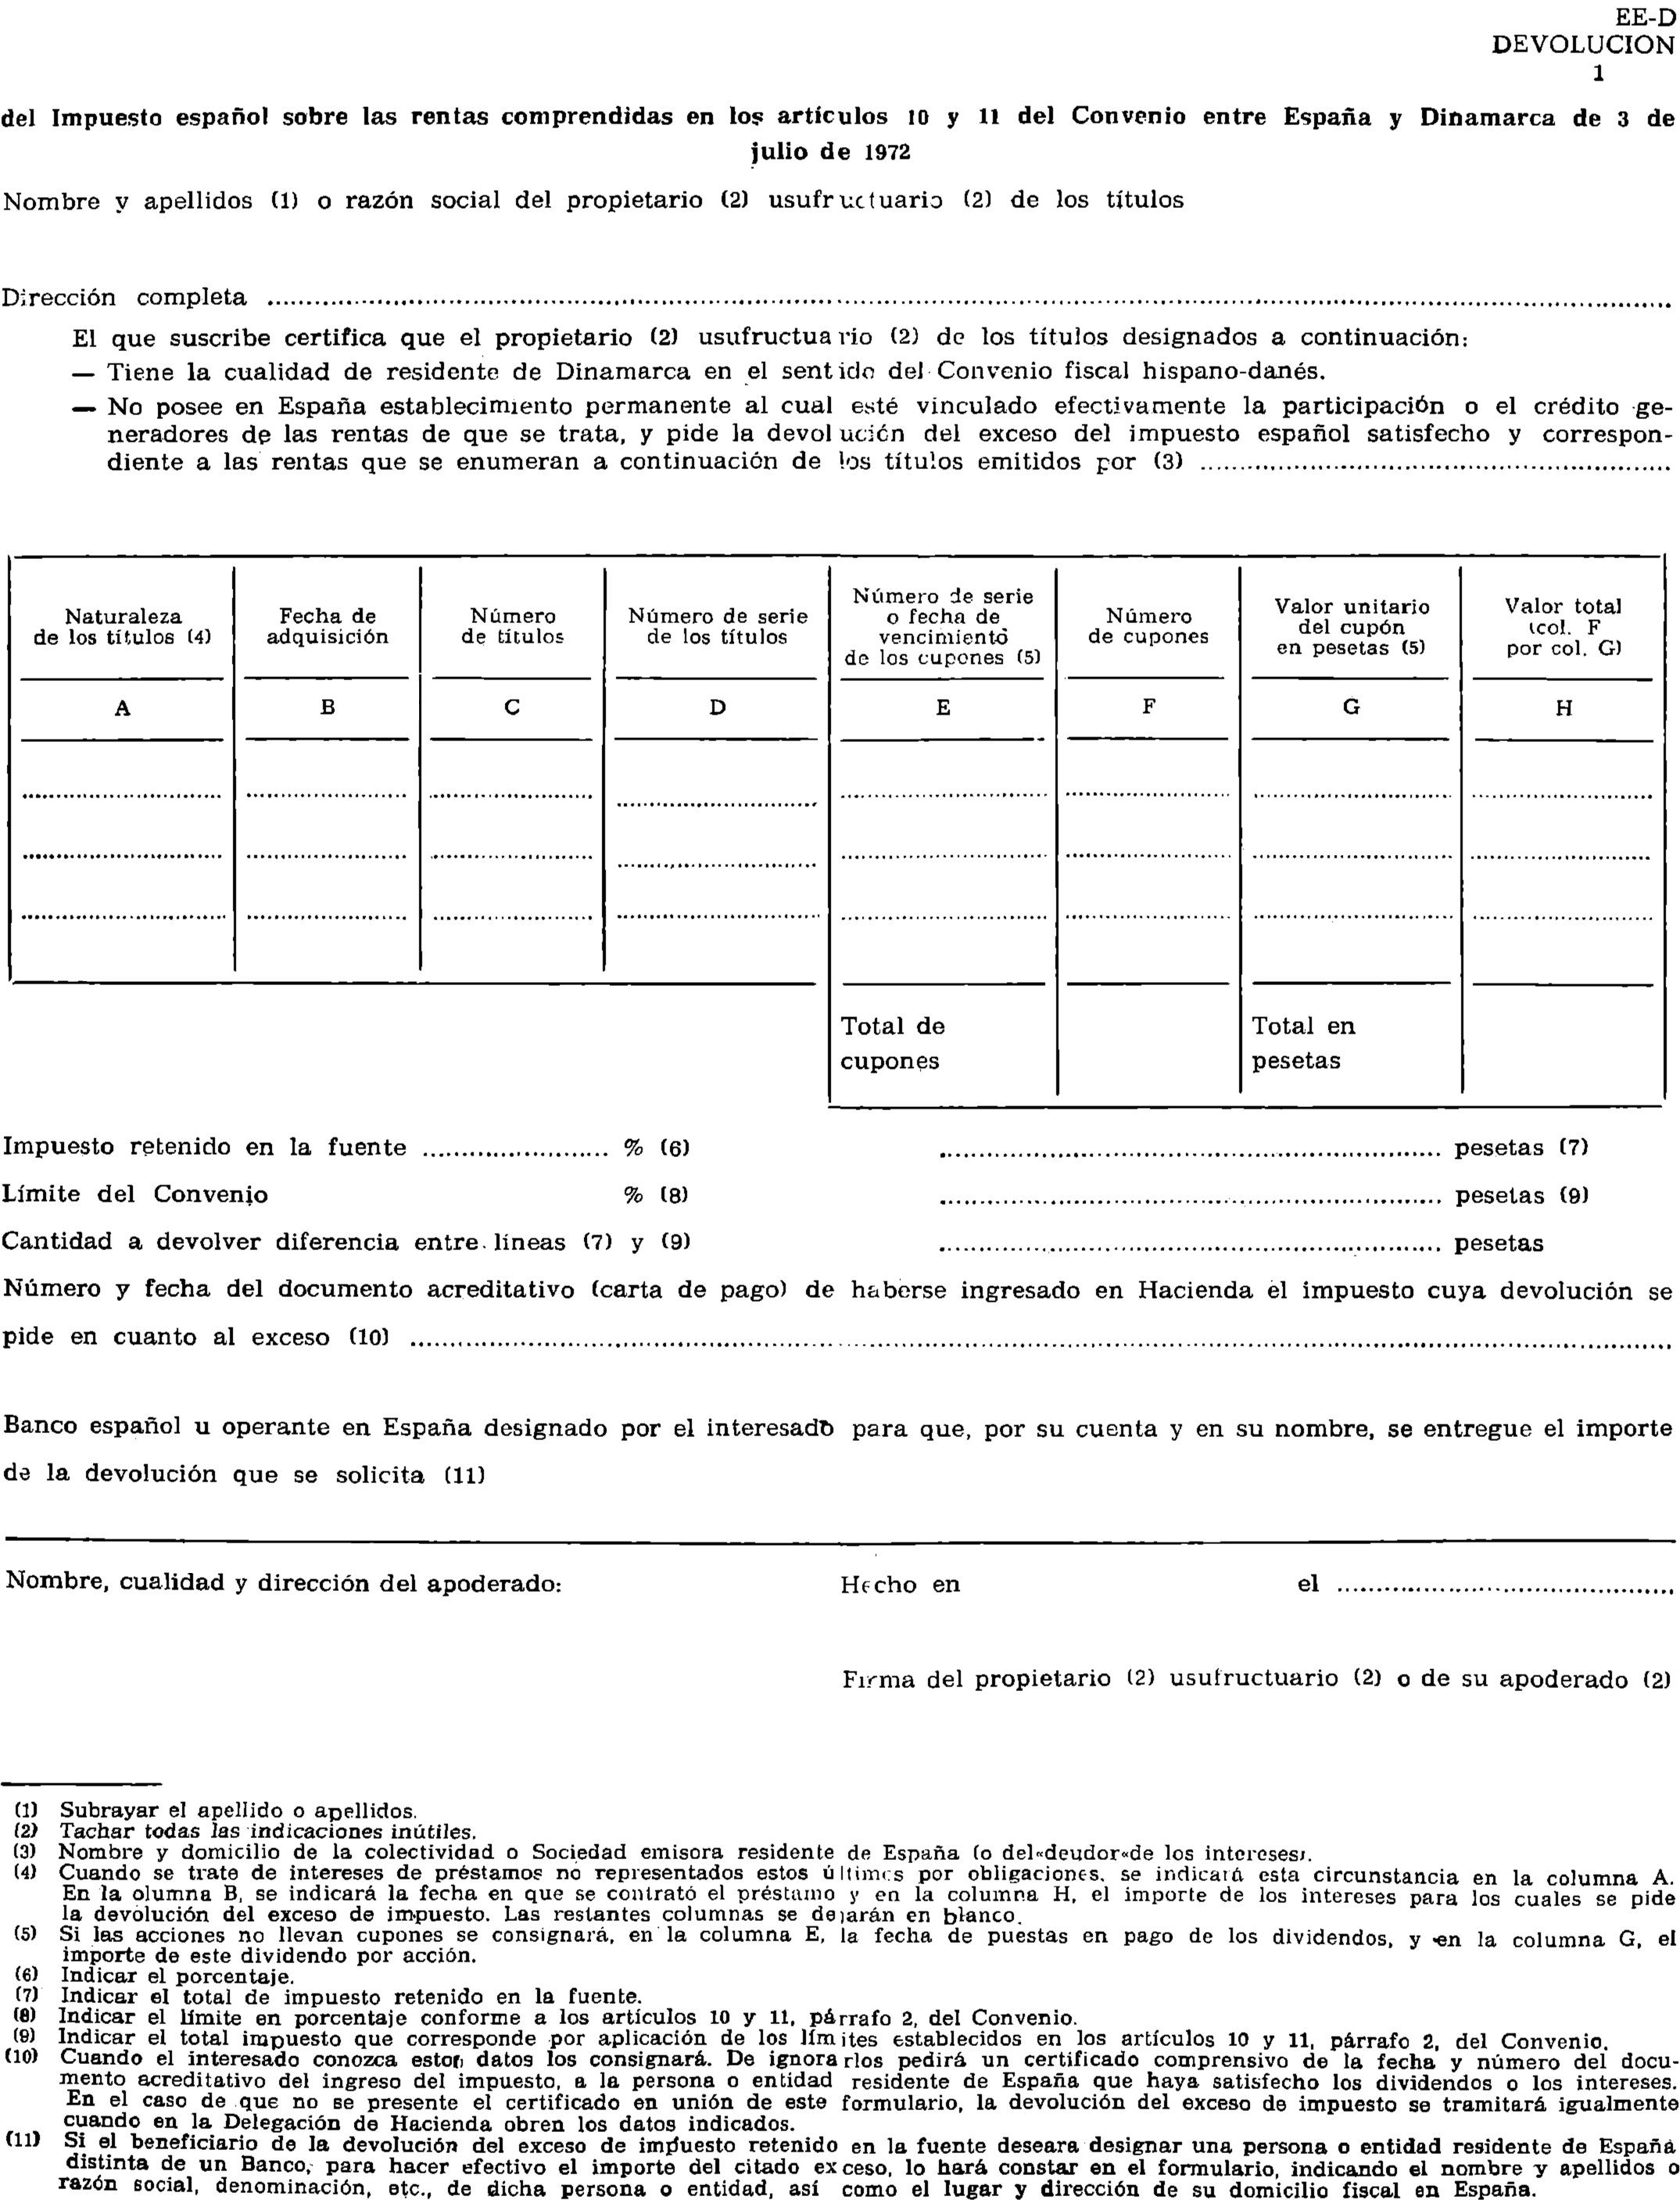
The application shall be made in model EE-D, Return (Annex III to this Order), which shall be provided by the Danish Tax Authorities. Completed the form and certified the residence by the competent tax office of Denmark, the copy, in Spanish, will be sent by the beneficiary or his representative to the Treasury Delegation of the domicile of the debtor of the income. One copy of the form, in Danish, shall be for the Danish tax authorities and the other, also in Danish, for the beneficiary himself.
This application must be accompanied by a certificate issued by the person or entity obliged to withhold the tax, stating the date and number of the letter of payment of the income, which includes the retention made to the beneficiary. Where the data are taken directly by the Administration, they shall be recorded in the file by means of diligence. If the certification is not accompanied by the application, or if the information must be entered in the respective Treasury Delegation, the Management Office shall require the applicant to make the request available within 30 days.
Where the beneficiary of the dividends or interest acts by means of a person representing him, he shall also join the request of the competent authority.
The request for repayment shall be made in the respective Treasury Delegation within one year, which shall begin to run from the following dates; in the case of dividends, after two months from the day on which the income was due; and in the case of interest, after the last day of the first month following the calendar quarter on which the interest was due.
The file shall be processed by the International Conventions Section, or, failing that, by the Office responsible for the Service, in the manner set out in article 6 of Decree No. 363/1971 of 25 February; the return agreement shall be issued by the respective Treasury Delegation.
(d) Several returns may be requested on the same form if all of them are within the time limit referred to in point (c) above and correspond to revenue made in the same Treasury Delegation.
(B) Income covered by article 12 of the Convention.
(a) The fees from Spain which they receive, persons or entities which, in accordance with Article 4 of the Convention, have the status of residents of Denmark, shall be taxed in Spain by withholding tax on the income of physical persons, within the limit laid down in Article 12 of the said text. This limited retention shall be applied by the resident debtor of Spain, without it being necessary for the creditor resident in Denmark to make any request to the Spanish tax authorities.
The tax declaration to be submitted by the debtor of the royalties shall necessarily state that the beneficiary of the royalties is resident in Denmark and shall also state the circumstances in the respective documents issued for the use or granting of the use of the rights and elements in general contained in Article 12 of the Convention. Such a declaration shall be accompanied by a document proving Denmark's resident status within the meaning of Article 4 of the Convention issued by the Danish Tax Authorities.
(b) Where the debtor of the fees retains Spanish tax, as a result of the application of the rules and tax rates contained in Spanish domestic law, as if there were no agreement, the person or entity resident in Denmark, who would benefit from such fees, may request the Spanish tax authorities to refund the excess Spanish tax retained at the source. No special form shall be required for the return request. The application shall be accompanied by a document proving the residence status of Denmark within the meaning of Article 4 of the Convention issued by the Danish tax authorities and the certification referred to in the third subparagraph of paragraph 2 (A) (c) of this Order, which includes the income of the royalty tax in question.
Except as regards the specific subject of forms, such refunds shall be governed by the provisions which, with reference to dividends and interest, are contained in paragraph 2 (A), (c).
Third. Certificates.
Within their respective powers of territorial order, the Sections of International Conventions of the Treasury Delegations, or, failing that, the Tax Clearing Offices agreed upon, shall, subject to appropriate checks, issue the residence certificates requested in writing, for the purposes of the application of the Convention, by persons and entities having the status of residents of Spain within the meaning of Article 4 of the Convention.
Without prejudice to the information and background provided by the Offices, proof of the fact of residence may be required of the applicant to show the national identity card, passport or proof of residence.
It shall also be the responsibility of the Offices concerned to issue such other certificates as may be requested by the persons or entities concerned, provided that they have as their object the application by Spain or Denmark of any of the provisions of the Convention.
What I communicate to V. I. for its knowledge and effects.
God save V. I. Many years.
Madrid, December 4, 1978.
FERNANDEZ ORDOÑEZ
Ilmo. Sir. Technical Secretary-General.
ANNEX I
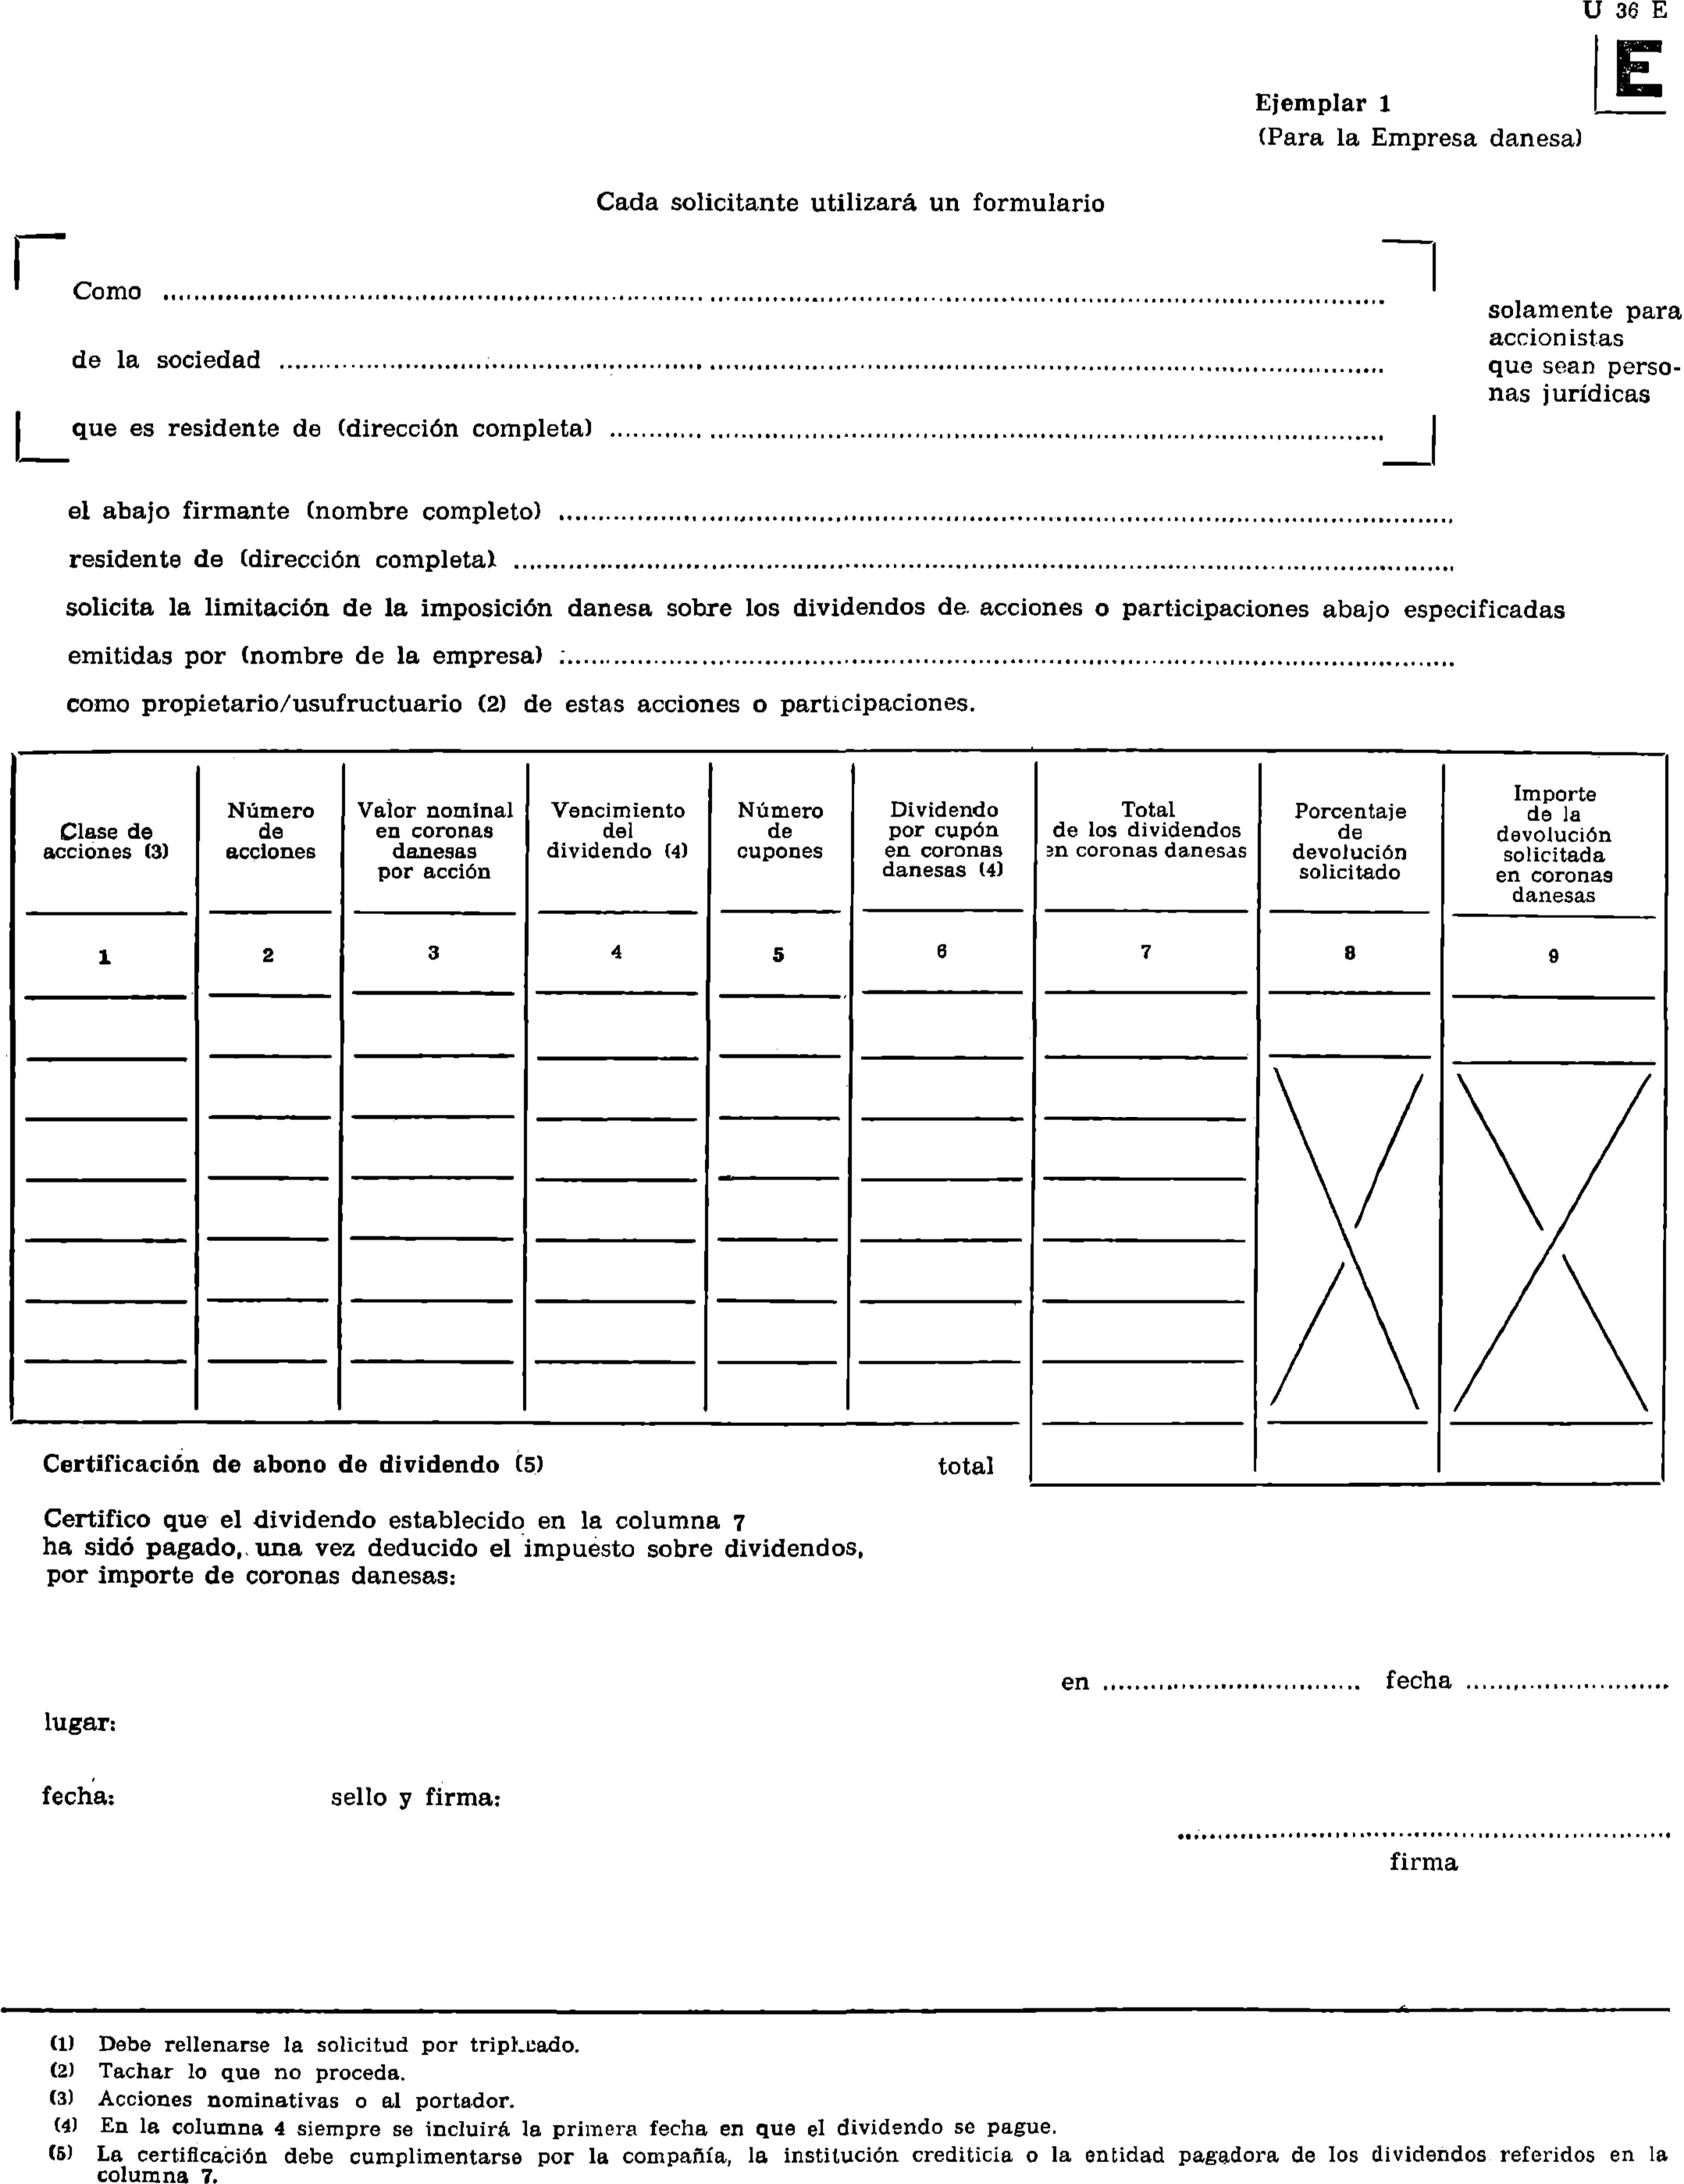
Request for refund of Danish dividend tax (1)
English rendering of a scanned annex (unverified OCR). The original facsimile is retained below for comparison.
Automatic English OCR transcription (unreviewed)
UU 36 E
Example 1 (For the Danish Company)
Each applicant shall use a form
⁇ A ⁇ only for shareholders of the Company ........ooococonononsen tantannoonnornnarntornonnan o ene No frog R eno naar non RORr RR UD Gara rar na rr ran nun rare no anna ner r ro norcrionnonasa que son perso- nas legales que es resident de (direction complete) ........ AN ⁇
the undersigned (full name) c..concccononenioncnonsacnanonononanonncnnnnnonarnonannonannonannonannonnannannannannn r r ari oronannin na noo nrrr car ronnan ano nanencrcinons
resident of (full address ....oonccooncnnananonnonnonnorons requests the limitation of the Danish tax on dividends of. below specified shares or shares
issued by (name of company) lm. Po...
as owner/usufructaire (2) of these shares or shares.
: Amount Number Nominal value ⁇ Expiration Number Dividend Total Percentage
Kind of in krone and per coupon of dividends of return shares (3) Danish shares dividend (4) coupons in krone 2n Danish crowns refund requested per Danish share (4) requested in krone
Danish
1 2 3 4 5 8 7 8 9 Total dividend fertilizer certification (5)
I certify that the dividend set out in column 7 has been paid, after deducting the dividend tax, in the amount of Danish kroner:
place:
date: stamp and signature:
(1) The application must be completed per tripluate.
(2) Delete as appropriate.
(3) Nominative or carrier actions.
(4) Column 4 shall always include the first date on which the dividend is paid.
(5) The certification must be completed by the company, credit institution or paying institution of the dividends referred to in column 7.
Original source facsimile
English rendering of a scanned annex (unverified OCR). The original facsimile is retained below for comparison.
Automatic English OCR transcription (unreviewed)
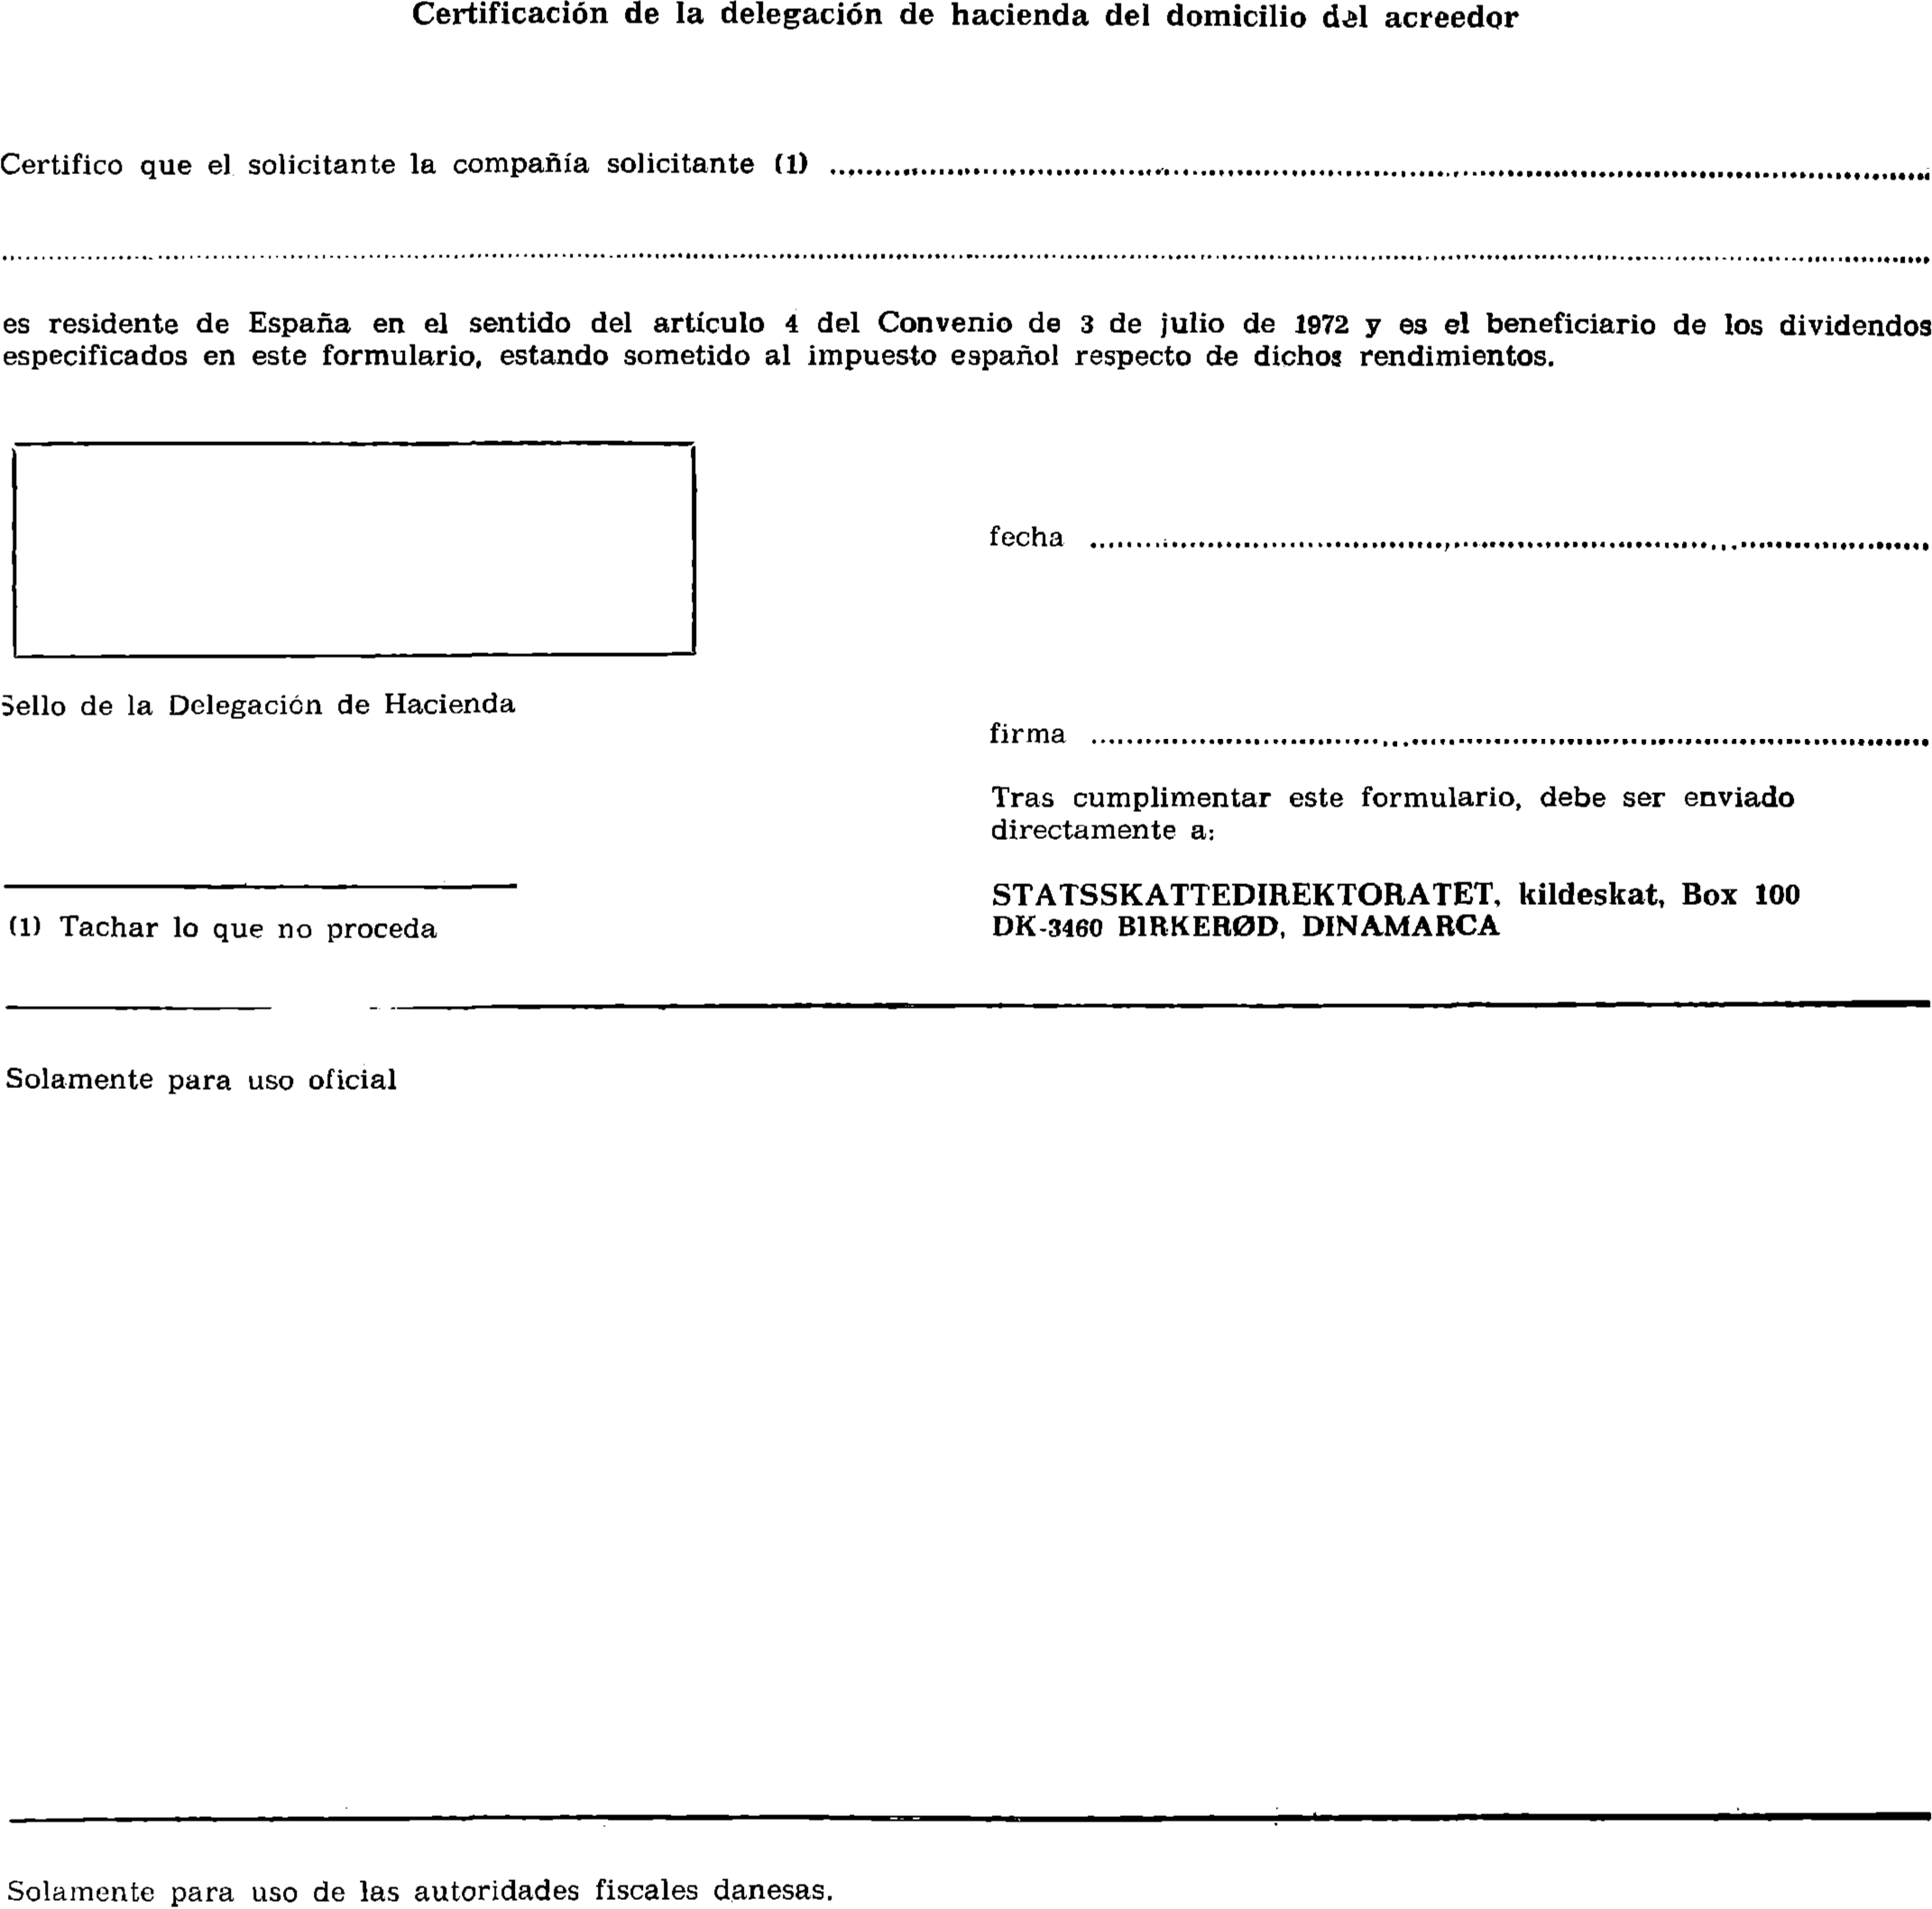
Certification of the delegation of property of the creditor's domicile
I certify that the applicant company (1) ..... isomnonvonconsosanoonncnnoneranoncononornonocrnonoanocr nono sr o nro oneponnora nc orcana Denronarnrioonron soriano
is resident of Spain within the meaning of Article 4 of the Convention of 3 July 1972 and is the beneficiary of the dividends specified in this form, being subject to the Spanish tax in respect of such returns.
3ello de la Delegation de Hacienda
(1) Delete where not applicable
or EA
(Arrrr Orrra Ion renn that
ITA o.occnnnonaneneconarnos
After completing this form, it must be sent directly to:
STATSSKATTEDIREKTORATET, kildeskat, Box 100 DK-3460 BIRKEROD, DENMARK
For official use only
Only for the use of the Danish tax authorities,
Original source facsimile
ANNEX II
Request for reduction
English rendering of a scanned annex (unverified OCR). The original facsimile is retained below for comparison.
Automatic English OCR transcription (unreviewed)
EE-D REDUCTION 1 and 2
of the Spanish Income Tax falling within Articles 10 and 11 of the Convention between Spain and Denmark of 3 July 1972
Name and surname (1) or business name of the owner (2) usufru actuario (2) of the titles .......ccconossarenonennaironnanconrorocsonooraron nooo
Full address ....omoomemmonccncnnoconoconononcnnarnoconnaronsocacniavanen >
The undersigned certifies that the owner (2) usufructaire (2) of the following titles:
— has the status of a resident of Denmark under the Spanish-Danish Tax Convention.
-— It does not have a permanent establishment in Spain to which it is effectively linked . the shareholding or the credit generated by the income in question, and calls for the reduction of the Spanish tax corresponding to the income which will be paid after the securities issued by (3) ............ ronannonno eenorannnncnnos dona nenennnnnnonnannornnnrinna rra rnarnnninnannonnninnnninnsa
(IR rr rr rr rr rr rr rr rr rr rr rr rr r r r r r r r r r r r r r r r r r r r r r r r r o r r r r r r r r r r r r r r r r r r r r r r r a r r r r r r r r r r r r rr r r r r r r r r r r r r r r r r r r r r r e r r r r r r r r r e r e r e r e r
Serial number
Number
Unit value of coupon
Total value (col.
Nature Date Number of serial number or date of e of expiry of pesetas F. per col. G.) securities (4) acquisition securities of Whones coupons or 5 5 A B Cc D E F G H
Total coupons
Total er. pesetas
Tax to be deducted per 100 (6)
Net dividend or net interest ......ooomocmcaomm*.o:
O AT
Made €N .occcoioicnnscoreconon
Name, quality and address of the representative..,
Signature of the owner (2) usufructaire (2) or his representative (2).
vv,
(1) Underline the last name(s).
(2) Delete all useless indications.
(3) Name and address of the issuing community or company resident in Spain (or debtor of interest).
(4) In the case of interest on loans, which are not represented by obligations, this shall be indicated in column A. In column B, the date on which the loan was contracted and in column H, the amount of interest for which the tax reduction is requested shall be indicated. The remaining columns will be left blank.
(5) If the shares do not bear coupons, the date of payment of the dividends shall be indicated in column E. and in column G, the amount of this dividend per share. a
(8) Consign the type agree!
Article 2 of the Convention and the amount of the Spanish tax which is retained at the source in accordance with Articles 10 and 11, paragraph 1.
Original source facsimile
English rendering of a scanned annex (unverified OCR). The original facsimile is retained below for comparison.
Automatic English OCR transcription (unreviewed)
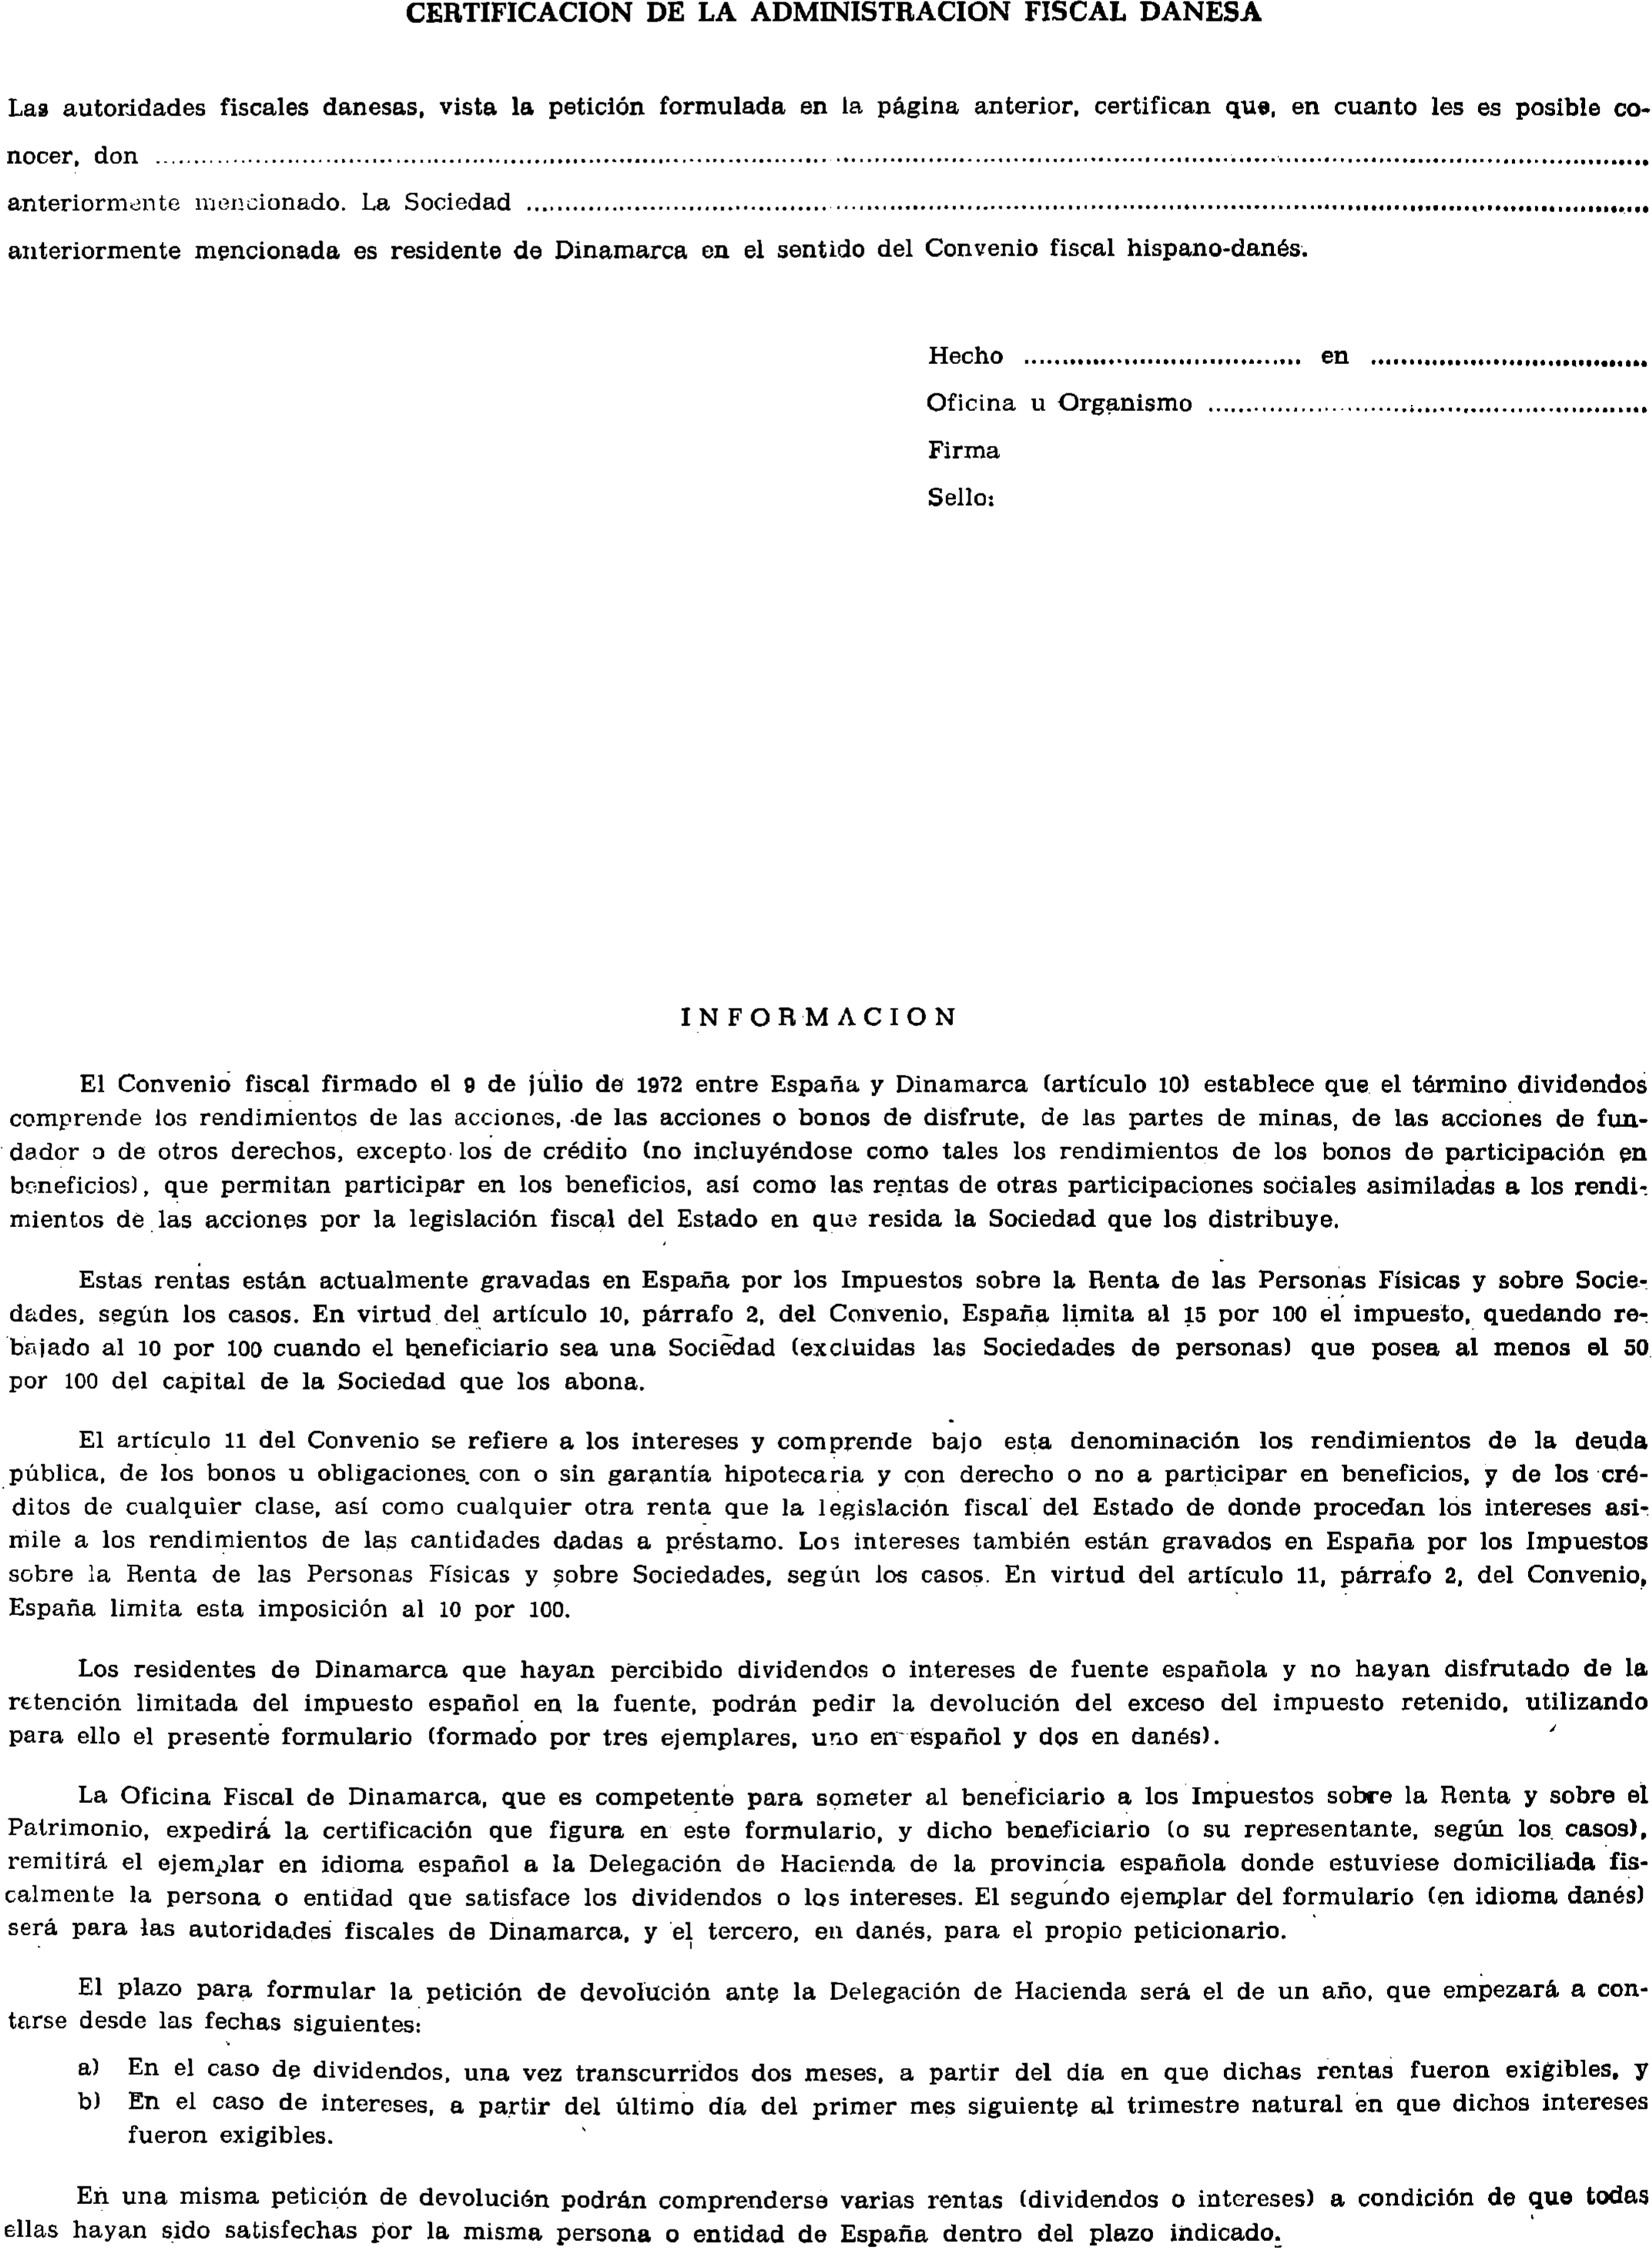
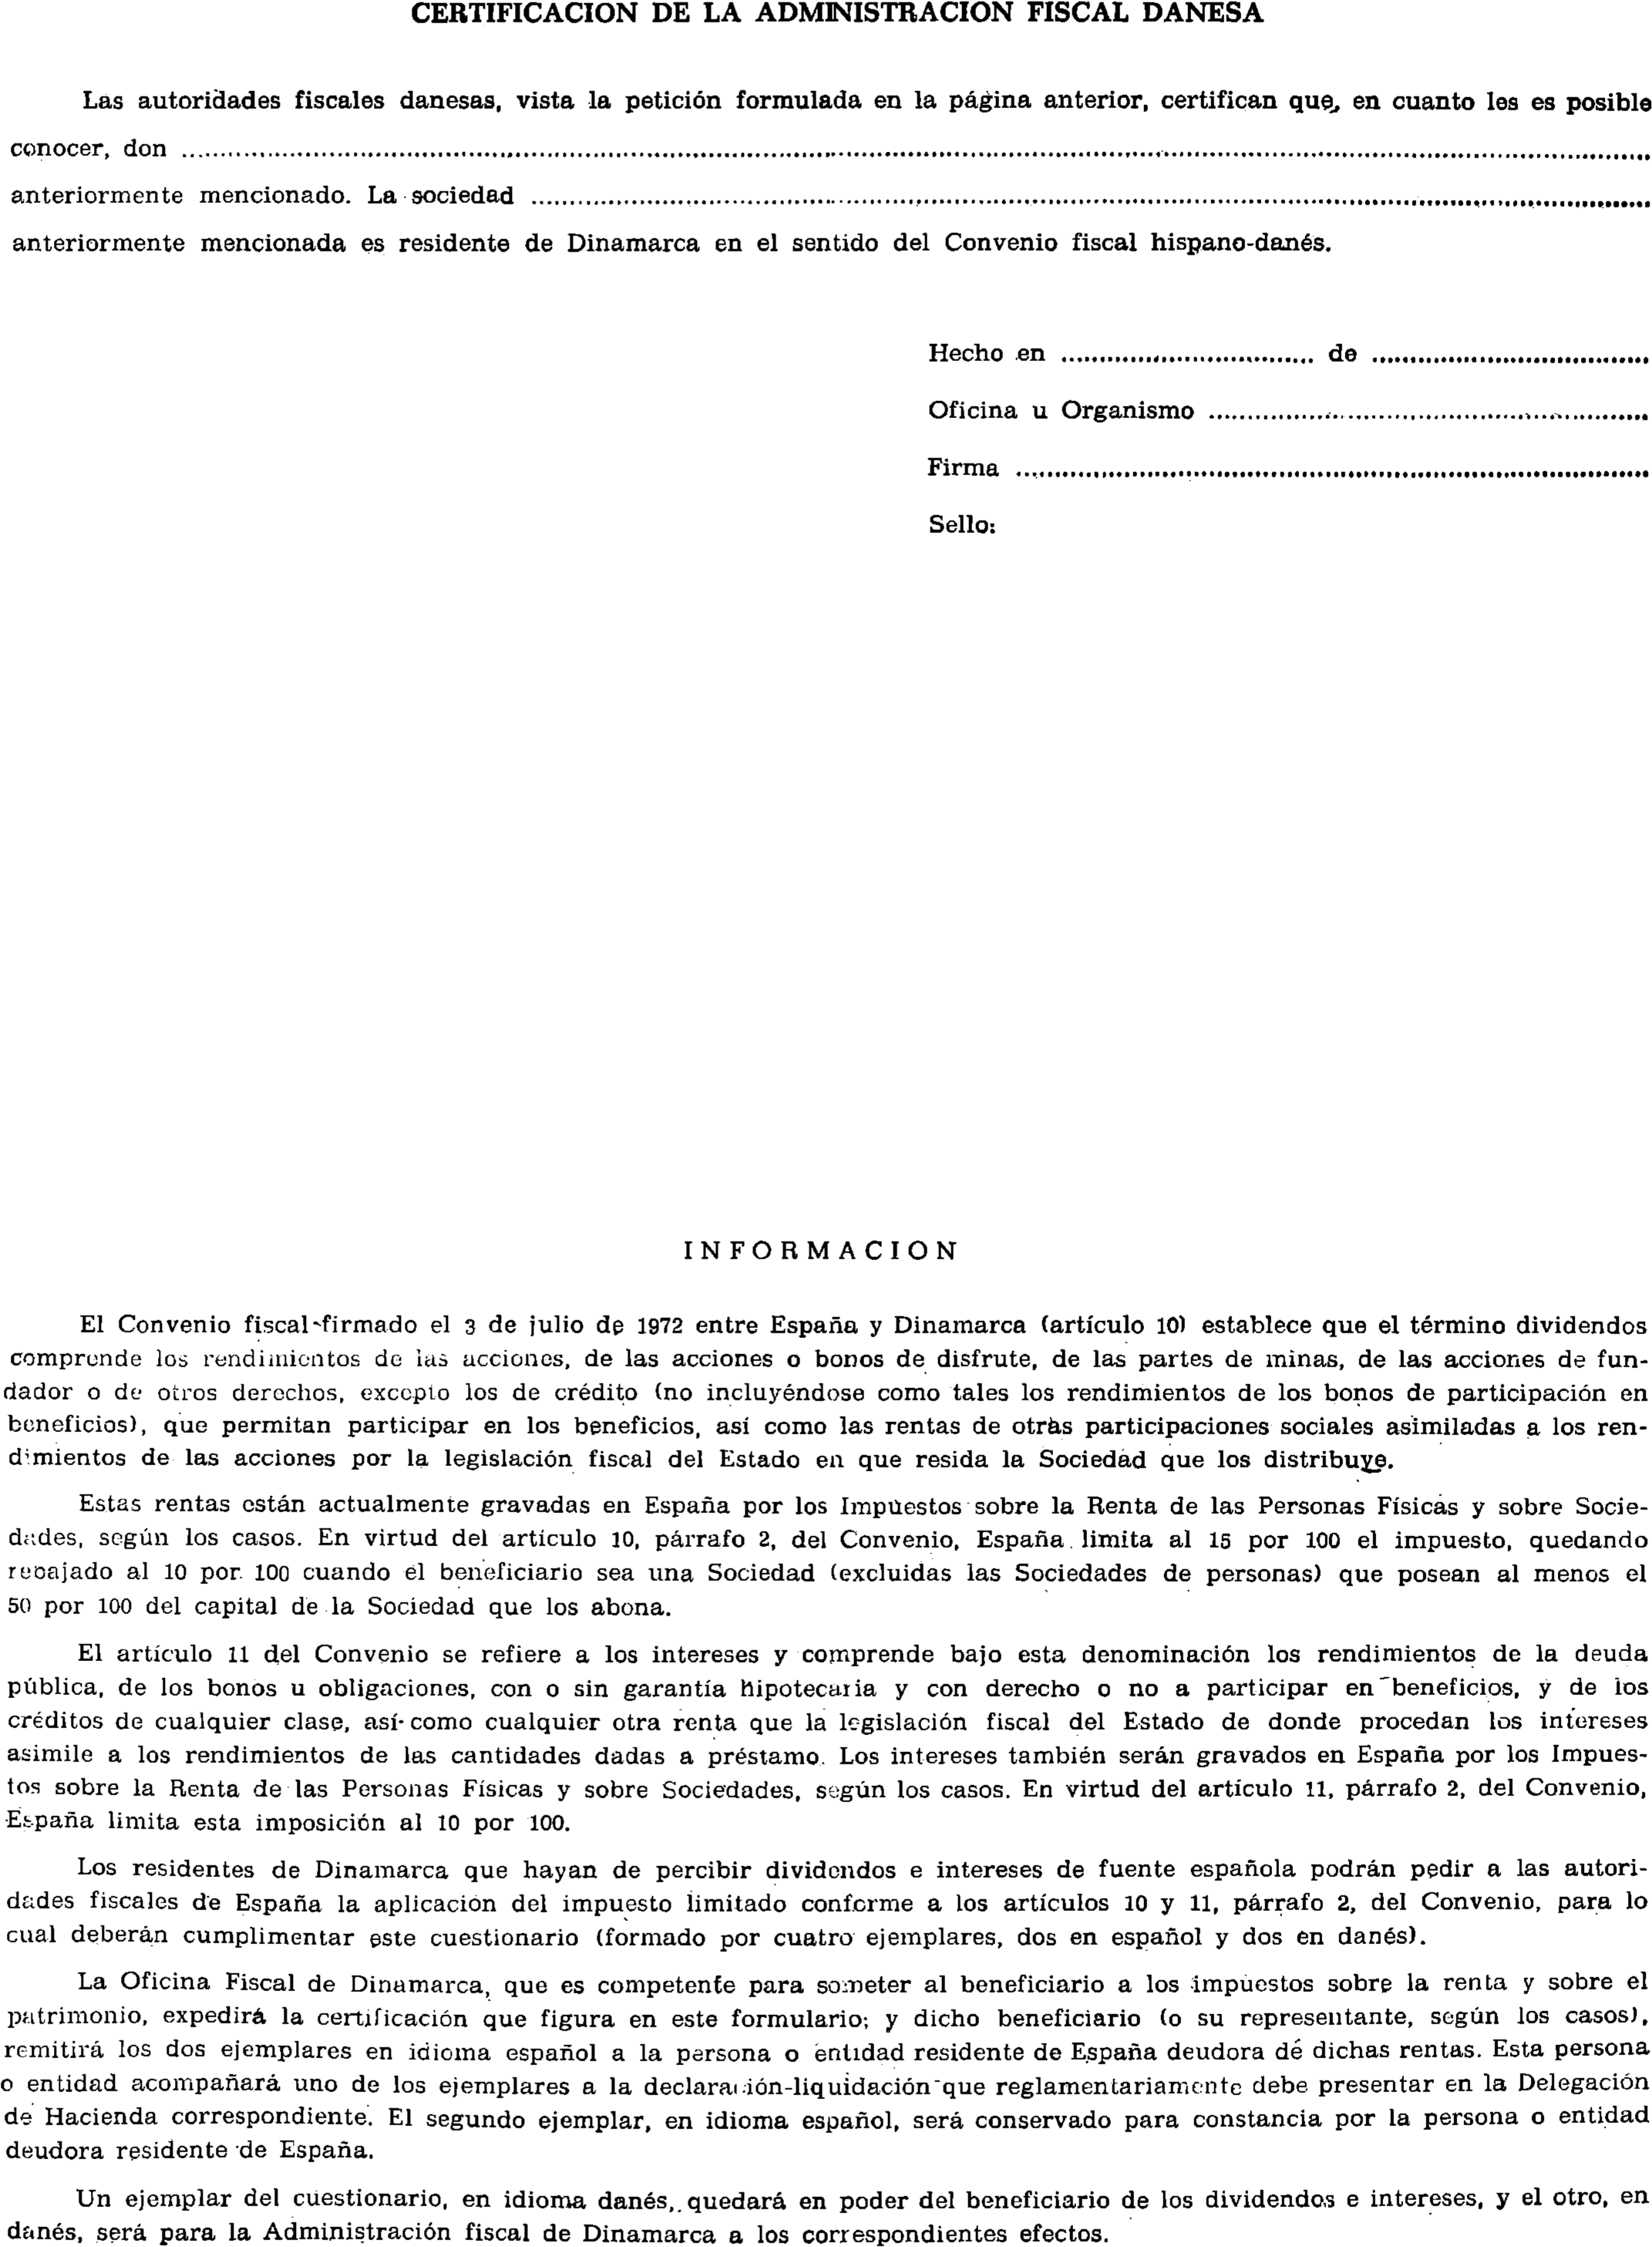
CERTIFICATION OF DANESE TAX ADMINISTRATION
The Danish tax authorities, having regard to the request made on the previous page, certify that, as soon as possible (9 TS SA ernannonnencanononenasenas Ona NOO rn Aron rare ra noro grudge onaranorococrnecororononso encsoros
mentioned above. The society .......orcorccncnroncccccanonoamonccnnonas Porno rona baby rene r on roonanunrenonsaconuoracenes Uncono nora daroarrq0sororacereos
mentioned above is resident of Denmark within the meaning of the Spanish-Danish Tax Agreement,
Done €D oosocrnononeoninoccanonous LO cosonnossocoraroooronenonaneness
Office or agency: [blank]. [Other form characters are unclear in the source OCR.]
FITIMA .ococcorccnononoornanennorrnoesa ro ro rum rvorernnnarrochronennconraconnos
Stamp:
INFORMATION
The Tax Convention signed on 3 July 1972 between Spain and Denmark (Article 10) provides that the term dividends includes the income from the investments, shares or vouchers, parts of the mines, shares of the giver or other rights, excluding those from credit (not including as such the income from the profit-sharing bonds), which allow participation in the profits, as well as the income from other social participations assimilated to the surrenders of the shares by the tax legislation of the State in which the distribution company resides.
These revenues are currently taxed in Spain by the Taxes on the Income of the Physical Persons and on Socie-des, as the case may be. By virtue of Article 10, paragraph 2, of the Convention, Spain.Jimita to 15 per 100 the tax, being removed to 10 per 100 when the beneficiary is a Company (excluding Companies of persons) that own at least 50 per 100 of the capital of the Company that pays them.
Article 11 of the Convention refers to interest and includes under this heading the income from public debt, bonds or bonds, with or without mortgage guarantee and entitled or not to participate in profits, and from credits of any kind, as well as any income other than the tax legislation of the State from which the interest derives assimilates to the income from the amounts lent. Interest will also be taxed in Spain by taxes on the income of physical persons and on companies, depending on the case. Under article 11, paragraph 2, of the Convention, Spain limits this tax to 10 per 100.
Residents of Denmark who are to receive dividends and interest from Spanish sources may request the tax authorities of Spain to apply the limited tax in accordance with Articles 10 and 11, paragraph 2, of the Convention, for which purpose they must complete this questionnaire (consisting of four copies, two in Spanish and two in Danish).
The Danish Fiscal Office, which is competent to subject the beneficiary to income and property taxes, shall issue the certification contained in this form; and that beneficiary shall, as the case may be, send the two copies in Spanish to the person or entity resident in Spain that is the debtor of such income. This person or entity shall accompany one of the copies to the declaration::ion-liquidation "which shall be submitted by regulation to the corresponding Treasury Delegation. The second copy, in Spanish, shall be kept for record by the resident debtor or entity of Spain,
One copy of the questionnaire, in Danish, shall be held by the beneficiary of the dividends and interest, and the other, in Danish, shall be held by the Danish tax administration for the corresponding purposes.
Original source facsimile
ANNEX III
Request for return
English rendering of a scanned annex (unverified OCR). The original facsimile is retained below for comparison.
Automatic English OCR transcription (unreviewed)
EE-D RETURN 1
of the Spanish Income Tax falling within Articles and 11 of the Convention between Spain and Denmark of 3 July 1972
Name (1) or business name of the owner (2) of the securities
Full address ....... enncnanenannonos ernnnarannns cesrannnns
The undersigned certifies that the owner (2) uses (2) of the following titles: — Has the status of resident of Denmark in the meaning of the Spanish-Danish Tax Agreement.
— does not have a permanent establishment in Spain to which the shareholding or credit is effectively linked, and requests the refund of the excess of the Spanish tax paid and corresponds to the incomes listed below in the securities issued by (3)
Serial number ams Nature Number Date Serial number or date of. Number Value Rad vo In of the securities (4) acquisition of titles of the securities of Yencimienón an of coupons in pesetas (5) per col G) A B Cc D E F G H Total in pesetas coupons Tax withheld at source ...... ennararenaranaonos % (6) eonenaninnnnos germano benonanooa terminals ennnnanniasanna. Pesetas (7) Convention limit % (8) een nora ra nnornnnnnnninnonranranunironones esevaccsrosarsa., Pesetas (9) Quantity to be returned difference between lines (7) and (9) AN ON Lennon A E
Number and date of the document attesting (letter of payment) if the tax to which the refund is due has been paid to the Treasury
asks about excess (10) .......
Spanish bank or operator in Spain designated by the interest to deliver the amount on its own behalf
of the refund sought (11)
Name, quality and direction of the proxy: Made in the
Signature of the owner (2) usufructaire (2) or his proxy (2)
(1) Underline the last name(s).
(2) Delete all useless indications,
(3) Name and address of the community or broadcasting company resident in Spain (or of the ‘interest debtor’).
(4) In the case of interest on loans not represented by bonds, this shall be indicated in column A. In column B, the date on which the loan was contracted shall be indicated and in column H, the amount of interest for which the refund of the excess tax is requested. The remaining columns will be left blank.
(5) If the shares do not bear coupons, the date of payment of the dividends shall be entered in column E, and ‘in column G, the amount of this dividend per share.
(6) Indicate the percentage.
(7) Indicate the total tax retained at source.
(8) Indicate the percentage limit in accordance with Articles 10 and 11, paragraph 2, of the Convention.
(8) Indicate the total tax corresponding to the application of the limits set out in Articles 10 and 11, paragraph 2, of the Convention.
(10) Where the data subject is aware of this, he shall record it. If you ignore them you will ask for a comprehensive certificate of the date and number of the document proving the income of the tax, to the person or entity resident of Spain that has satisfied the dividends or the interest.
If the certificate is not submitted together with this form, the refund of the excess tax shall also be processed.
when the information indicated is made available to the Treasury Delegation.
If the beneficiary of the refund of the excess tax withheld at the source wishes to designate a person or entity resident in Spain
other than a bank, in order to give effect to the amount of such excess, it shall enter it on the form, indicating the name or surname or
the company name, etc., of that person or entity, as well as the place and address of his tax domicile in Spain.
(11)
Original source facsimile
English rendering of a scanned annex (unverified OCR). The original facsimile is retained below for comparison.
Automatic English OCR transcription (unreviewed)
CERTIFICATION OF DANESE TAX ADMINISTRATION
The Danish tax authorities, having regard to the request made on the previous page, certify that, as soon as possible co-MOCEL, DOM cooccccniccnnconnnaccannannnrononnnnonoronnos ronunoronase erennanrnnnnananonos January nao ere nn rec nnaa creates ronarinnnnons erunaarnonsanononians: eonocansonons eorerenoranoonosss eonoussonos mentioned above. The Society .....ccoccocononcrocnneronanos eneneccncncansansans eononerenaninnns ernenrcnononena erennorcannocrnarnas III NO UnNrrOnUe rronorcnacinnanoronroo
He is a resident of Denmark within the meaning of the Spanish-Danish Tax Agreement.
Done at [blank]. Office or agency [blank]. Signature [blank]. Seal [blank]. [Other form characters are unclear in the source OCR.]
INFORMATION
The Tax Convention signed on 9 July 1972 between Spain and Denmark (Article 10) provides that the term dividends includes the returns on shares, «of shares or bonds of enjoyment, of parts of mines, of shares of fundor or of other rights, except those of credit (not including as such the returns of the bonds of participation in profits), which allow to participate in the profits, as well as the income of other social participations assimilated to the surrenders of shares by the tax legislation of the State in which the company that distributes them resides.
These incomes are currently taxed in Spain by the Taxes on the Income of Physical Persons and on Socie-des, as the case may be. Under article 10, paragraph 2, of the Convention, Spain limits the tax to 15 per cent, falling to 10 per cent where the beneficiary is a corporation (excluding companies of persons) holding at least 50 per cent of the capital of the company that pays them.
Article 11 of the Convention refers to interest and includes under this heading the income from public debt, bonds or bonds, with or without mortgage guarantee and entitled or not to participate in profits, and from 'credits of any kind, as well as any other income derived from the tax legislation of the State from which the interest derives as such from the income from the amounts lent. Interest is also taxed in Spain by taxes on the income of physical persons and on companies, depending on the case. Under article 11, paragraph 2, of the Convention, Spain limits this tax to 10 per 100.
Residents of Denmark who have received dividends or interest from Spanish sources and have not enjoyed the limited retention of the Spanish tax at the source may request the refund of the excess of the tax withheld, using this form (made up of three copies, one in Spanish and two in Danish). !
The Danish Tax Office, which is competent to subject the beneficiary to income and property taxes, shall issue the certification contained in this form, and the beneficiary (or his representative, as the case may be), shall forward the Spanish-language copy to the Delegation of Finance of the Spanish province where the person or entity satisfying the dividends or interest is domiciled. The second copy of the form (in Danish) will be for the Danish tax authorities, and the third, in Danish, for the petitioner himself. :
The deadline for making a request for repayment to the Treasury delegation shall be one year, which shall begin from the following dates:
(a) in the case of dividends, after two months, from the day on which those income was due, and (b) in the case of interest, from the last day of the first month following the calendar quarter in which those interest was due. :
Several income (dividends or interest) may be included in the same return request provided that all of them have been paid by the same person or entity in Spain within the specified time limit.
Original source facsimile